Assets

iPulse AI Editorial Picks research

Best US Stocks

Explore the best US stocks according to iPulse AI's independent agentic investment research. The analysis combines one-year return potential with five-year trend confirmation, multi-agent consensus, business quality, financial health, valuation and risk resilience. Every selection includes a clear investment thesis, projected returns, catalysts and the risks that could change the outlook, helping investors compare high-conviction ideas using evidence rather than a single score or short-term price move.

Editorial ApproverRusslan Ramdowar iPulse AI Engine V6 15 min read
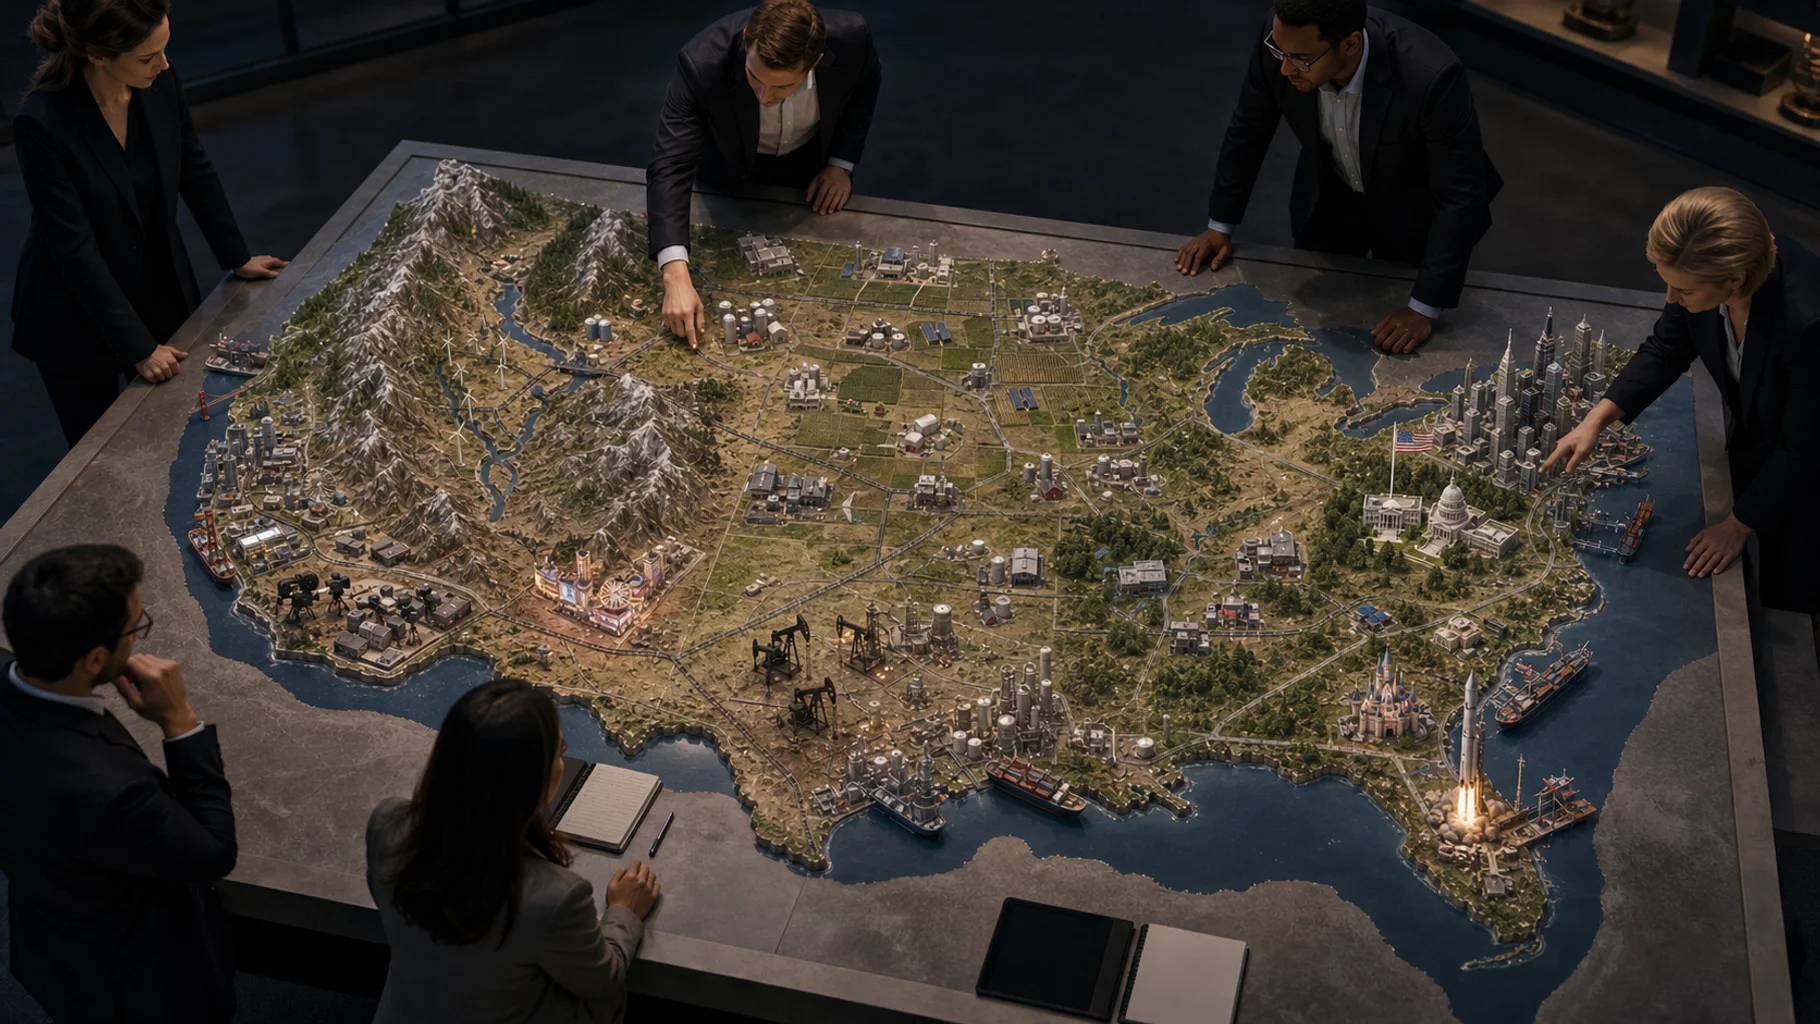
Equity analysts study a detailed United States economic map showing government, finance, technology, energy, aerospace, entertainment, agriculture, ports, logistics, and regional geography.

Our Approach: Our research starts with about 100,000 stocks. For this edition, 376 assets passed preselection and underwent deep multi-agent analysis. iPulse AI Engine V6 ranked the top 10, and 10 Editorial Top Picks passed the separate evidence review and approval workflow. Read the detailed methodology

Editorial Picks countdown

Top 10 Editorial Picks

UNH:NYSEHQ:Listed:

Health Care · Managed Health Care

Diversified healthcare company providing health insurance and healthcare services through UnitedHealthcare and Optum divisions.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

The company's massive cash reserves ensure that dividends and share buybacks remain fully funded and secure.

What to watch

A Doj mandated structural breakup could restrict market access and weaken the investment case.

+89.9%
Excl. dividends: +80.2%
1.1%Dividend yield (net)
0.0%Buyback yield
25.5x
32/100
85/100

Flagship insight

Why This Healthcare Giant's Strategic Membership Cuts Signal A Massive Margin Rebound

High consensus across reports indicates that strategic membership pruning and agentic AI deployment will drive a structural margin recovery, offsetting regulatory headwinds. While federal rate freezes and antitrust litigation present persistent frictions, the enterprise's vertical integration and robust claims float provide an unassailable defensive cash-flow floor.

The company is currently going through a temporary rough patch, but its core business remains incredibly strong. By intentionally letting go of more than one million unprofitable insurance members, management is successfully focusing on profitability over sheer size. At the same time, the company is investing heavily in artificial intelligence to automate paperwork and lower administrative costs. This strategic shift, combined with the company's massive cash generation, ensures it can easily weather government rate cuts and ongoing legal challenges.

  • Letting go of high-cost insurance members quickly restores profitability and protects the company's cash flow.
  • Heavy investments in artificial intelligence will automate claims processing and significantly lower daily operating expenses.
  • High interest rates allow the company to earn substantial interest income on the cash it holds before paying out claims.
  • Government rate freezes and antitrust lawsuits will continue to cause stock price volatility in the near term.
  • The company's massive cash reserves ensure that dividends and share buybacks remain fully funded and secure.
  • Everyday investors should look past temporary bad news and focus on the company's unmatched role in the healthcare system.

Advisor consensus

The primary disagreement across reports centers on the long-term viability of the vertical integration model under intense regulatory scrutiny. Some analyses assume that antitrust pressures and flat Medicare Advantage rates will permanently compress margins, transitioning the company into a slow-growth utility. Conversely, other reports argue that the company's massive scale and rapid deployment of agentic artificial intelligence will easily bypass these headwinds, driving a powerful margin expansion that is completely un-modeled by the consensus. There is also minor disagreement regarding the timing of the margin recovery, with estimates for full normalization ranging from late 2026 to 2028.

Risk and opportunity map

Longer-term opportunities

Optum Spin-Off Value Unlock

Capital Allocation

20% probabilityStock price impact: +25.0%Earnings impact: Not quantified

Regulatory pressure could compel a proactive spin-off of the high-growth, technology-enabled services division from the heavily regulated insurance unit. Decoupling these entities would eliminate the conglomerate discount and allow the market to apply a premium technology multiple to the standalone services business, violently unlocking substantial shareholder value.

Sweeping Medicare Privatization Mandate

Macroeconomic And Macrofinancial

25% probabilityStock price impact: +18.0%Earnings impact: Not quantified

To address the federal debt crisis, the government could aggressively privatize the remaining traditional Medicare population into managed care. This policy shift would instantly expand the company's total addressable market by millions of new members, driving an unprecedented multi-year revenue re-rating and solidifying its role as critical national infrastructure.

Tail risks

DOJ Mandated Structural Breakup

Regulatory

15% probabilityStock price impact: -35.0%Earnings impact: Not quantified

A successful antitrust lawsuit could force the complete structural separation of the insurance arm from the provider and pharmacy benefit segments. Shattering this vertical integration would destroy internal synergies, eliminate dual-margin capture, and expose both entities to raw market competition, leading to a severe and permanent de-rating of the stock.

Catastrophic Cyber-Contagion Event

Operational Efficiency

10% probabilityStock price impact: -30.0%Earnings impact: Not quantified

A secondary, prolonged state-sponsored cyberattack could completely paralyze the centralized clearinghouse infrastructure for over thirty days. This would trigger catastrophic cash-flow interruptions, invite draconian federal oversight, and result in multi-billion dollar remediation charges and provider loans, temporarily wiping out a full year of operating earnings.
IBM:NYSEHQ:Listed:

Information Technology · IT Consulting & Other Services

Global technology and consulting company providing integrated solutions leveraging AI, cloud, and data platforms.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Recent software purchases are creating a highly profitable, recurring revenue stream that is difficult for competitors to disrupt.

What to watch

A Red hat open source displacement could erode market share and pricing power.

+94.4%
Excl. dividends: +75.0%
2.1%Dividend yield (net)
0.0%Buyback yield
20.9x
44/100
76/100

Flagship insight

Why Regulated Sovereign AI Mandates Are Quietly Reshaping Enterprise Tech Infrastructure

High consensus reveals a structural pivot toward sovereign AI and hybrid cloud orchestration, offsetting legacy consulting deceleration. While multiple expansion remains a point of sharp divergence, robust free cash flow and regulatory capture via federal mandates provide a defensive floor against macroeconomic and monetary headwinds.

The company is successfully transforming from an old-school hardware maker into a modern software and cloud security powerhouse. This shift is highly profitable because businesses and governments are facing strict new rules about where they can store and process their data. Instead of using public cloud giants, many regulated organizations are choosing this company's secure, private hybrid cloud systems. While some investors worry the stock has run up too fast, its massive cash generation and reliable dividend payments offer a strong safety net during times of market volatility.

  • Strict government rules on data privacy are forcing large organizations to use secure, private cloud software.
  • Recent software purchases are creating a highly profitable, recurring revenue stream that is difficult for competitors to disrupt.
  • The company's massive cash flow easily supports its attractive dividend, providing a reliable shield for conservative investors.
  • High interest rates and a slowing global economy could cause corporate clients to delay large, expensive consulting projects.
  • New artificial intelligence tools could automate basic tasks, reducing the need for expensive human consultants over time.
  • The stock's current valuation is historically high, meaning any growth slowdown could lead to temporary price drops.

Advisor consensus

The primary disagreement across the reports centers on the valuation multiple and the growth horizon. Skeptics argue that the current multiple is highly fragile, driven by a cyclical mainframe refresh and temporary artificial intelligence consulting hype that will soon roll over. Conversely, structural bulls contend that the software mix shift, recurring revenue from recent acquisitions, and sovereign data mandates represent a permanent, non-cyclical transformation that justifies a sustained premium multiple. There is also minor disagreement regarding the speed at which autonomous AI will cannibalize traditional consulting revenues.

Risk and opportunity map

Longer-term opportunities

Quantum Computing Commercial Breakout

Innovation And Product

25% probabilityStock price impact: +30.0%Earnings impact: Not quantified

The early commercialization of fault-tolerant quantum computing would establish a monopolistic moat in molecular simulation, logistics, and cryptography. This breakthrough would instantly re-rate the asset from a mature IT provider to a frontier-tech pioneer, unlocking entirely new high-margin revenue streams and driving massive multiple expansion.

Sovereign Cloud Mandate Expansion

Regulatory

35% probabilityStock price impact: +20.0%Earnings impact: Not quantified

Draconian data localization laws legally preclude the use of public cloud environments for critical infrastructure, defense, and healthcare AI workloads. This regulatory shift would grant the asset a virtual monopoly on compliant, air-gapped hybrid deployments, triggering a massive super-cycle in software licensing.

Tail risks

Red Hat Open-Source Displacement

Competitive Positioning

25% probabilityStock price impact: -30.0%Earnings impact: Not quantified

A coalition of hyperscalers and open-source foundations successfully standardizes a free, lightweight container orchestration layer that bypasses OpenShift. This would destroy the asset's primary hybrid cloud moat, rendering its multi-billion-dollar software acquisitions economically stranded and severely impairing long-term software margins.

Catastrophic Mainframe Cyber Breach

Operational Efficiency

10% probabilityStock price impact: -40.0%Earnings impact: Not quantified

A state-sponsored cyber penetration successfully breaches the zSystems mainframe architecture, which serves as the backbone of global financial clearing. This security failure would instantly evaporate the switching-cost moat, forcing panic-driven migrations away from the platform and causing permanent capital impairment.

HUMA:NASDAQHQ:Listed:

Health Care · Biotechnology

Biotechnology company developing bioengineered human tissue products for vascular trauma, dialysis access, and regenerative medicine.

RatingBuy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

The company's main technology is highly advanced and has already proven successful in major clinical trials.

What to watch

A FDA response letter on dialysis could restrict market access and weaken the investment case.

+361.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
0.0x
24/100
1/100

Flagship insight

How a Mispriced Biomanufacturing Moat Prepares for a Massive Clinical Inflection

There is high consensus that the asset faces severe near-term liquidity pressure and dilution risks. However, a sharp divergence exists regarding long-term survival, with some projecting terminal capital starvation while others highlight a massive, de-risked clinical opportunity in hemodialysis supported by strategic domestic biomanufacturing infrastructure.

This company has developed a groundbreaking medical technology that grows human-like blood vessels that the body does not reject. However, the company is currently running out of money and has had to issue new shares, which has hurt the stock price. While the stock looks highly risky today due to these financial struggles, the underlying technology is highly valuable. The company is transitioning from a small, emergency-room market to a much larger, planned market for kidney dialysis patients, which could completely turn the business around if approved by regulators.

  • The company's main technology is highly advanced and has already proven successful in major clinical trials.
  • Recent stock sales have diluted current shareholders but provided a necessary cash bridge to survive the next year.
  • A major upcoming decision by the FDA for kidney dialysis use could act as a massive positive trigger for the stock.
  • Strong relationships with global medical networks could help the company distribute its products without expensive sales teams.
  • The biggest risk is that the company runs out of cash or faces regulatory delays before it can achieve profitable commercial sales.
  • Retail investors should treat this as a high-risk, high-reward opportunity with significant short-term volatility.

Advisor consensus

The primary disagreement across the reports centers on the investment horizon and the weighting of insolvency risk versus intellectual property value. Bearish perspectives adopt a near-term, purely quantitative lens, arguing that relentless dilution and unabsorbed manufacturing overhead will destroy common equity before commercial scale is reached. Conversely, constructive views emphasize a longer-term, asset-centric horizon, asserting that the clinical superiority of the dialysis indication and the strategic value of the domestic biomanufacturing facility establish an asymmetric floor that outweighs near-term balance sheet fragility.

Risk and opportunity map

Longer-term opportunities

Strategic Buyout by Major MedTech

Competitive Positioning

35% probabilityStock price impact: +200.0%Earnings impact: Not quantified

A well-capitalized medical device titan or major renal care partner determines that acquiring the company outright is cheaper than paying long-term royalties. At a depressed valuation, the acquirer can absorb the proprietary IP and domestic manufacturing infrastructure for a fraction of replacement cost, delivering an immediate, massive premium to shareholders.

Total DoD Stockpile Mandate

Political And Geopolitical

25% probabilityStock price impact: +150.0%Earnings impact: Not quantified

In response to escalating global kinetic conflicts, the US military invokes emergency procurement mandates to execute a large-scale, multi-year stockpiling contract for trauma vessels. This non-dilutive capital injection would instantly repair the balance sheet, bypass commercial distribution hurdles, and validate the platform globally.

Tail risks

FDA Complete Response Letter on Dialysis

Regulatory

30% probabilityStock price impact: -90.0%Earnings impact: Not quantified

The FDA issues a Complete Response Letter denying approval for the hemodialysis indication due to manufacturing facility discrepancies or requests for supplementary clinical data. Given the company's limited cash runway, a multi-year delay would fatally fracture the balance sheet, forcing catastrophic dilution or Chapter 11 restructuring.

Liquidity Crisis and Chapter 11 Reorganization

Capital Allocation

25% probabilityStock price impact: -85.0%Earnings impact: Not quantified

Ongoing cash burn exhausts remaining reserves before the dialysis indication achieves commercial profitability. If capital markets remain closed or highly punitive, the company is forced into a distressed restructuring where creditors seize the intellectual property and physical assets, completely wiping out common equity.

ISRG:NASDAQHQ:Listed:

Health Care · Health Care Equipment

Robotic-assisted surgery company known for the da Vinci Surgical System and minimally invasive procedure platforms.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

The company makes most of its money from selling recurring supplies and accessories, which keeps cash flowing even during economic downturns.

What to watch

A Cyber or AI malfunction could damage trust, security, and adoption.

+98.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
41.9x
76/100
62/100

Flagship insight

Why This High-Multiple Medical Technology Giant Faces A Hidden Valuation Gravity

There is high consensus that this medical robotics leader possesses an exceptional recurring revenue model and a pristine balance sheet. However, sharp divergence exists regarding near-term valuation multiple compression under restrictive monetary policy, as high interest rates threaten hospital capital budgets and pharmaceutical innovations pressure bariatric procedure volumes.

This company is a world leader in robotic surgery, making it a highly reliable and profitable business. However, the stock is currently very expensive, meaning that even if the company performs perfectly, the stock price might not grow as fast as its earnings. Everyday investors should expect steady growth in the company's core business, but must be prepared for stock price ups and downs as the market adjusts to higher interest rates.

  • The company makes most of its money from selling recurring supplies and accessories, which keeps cash flowing even during economic downturns.
  • A new robotic system rollout is forcing hospitals to upgrade, locking in customers for many years to come.
  • The company has almost zero debt and billions in cash, making it incredibly safe from financial trouble.
  • Because the stock is priced for absolute perfection, any small business delay could cause the stock price to drop temporarily.
  • New weight-loss drugs are reducing the need for weight-loss surgeries, creating a small but manageable headwind for the business.
  • The company is collecting massive amounts of surgical data, which will help it lead the future of artificial intelligence in healthcare.

Advisor consensus

The primary disagreements across the reports center on the severity of near-term multiple compression and the velocity of the next-generation upgrade cycle. Some perspectives assume that hospital capital constraints and high interest rates will severely delay system placements, forcing a painful multiple contraction toward historical averages. Other views argue that the platform's labor-saving efficiency makes it non-discretionary, allowing the upgrade cycle to defy macro headwinds. Additionally, there is minor disagreement regarding the long-term threat of pharmaceutical weight-loss drugs on overall procedure volumes, with some modeling permanent structural demand destruction and others viewing it as a temporary narrative overhang.

Risk and opportunity map

Longer-term opportunities

Level-3 Autonomous Surgical Clearance

Innovation And Product

25% probabilityStock price impact: +35.0%Earnings impact: Not quantified

The regulatory authority clears fully autonomous surgical sub-routines for specific high-volume, low-complexity tasks without real-time human intervention. This transitions the platform from a mechanical tool to a labor-replacement artificial intelligence entity, expanding the addressable market exponentially as surgical throughput becomes decoupled from human surgeon fatigue limits.

Bio-Data and Software SaaS Monetization

Innovation And Product

35% probabilityStock price impact: +20.0%Earnings impact: Not quantified

The company successfully launches a high-margin software-as-a-service subscription tier to monetize its multi-petabyte library of surgical telemetry. By allowing pharmaceutical and biotech firms to train on spatial outcomes, the firm creates a high-margin software revenue stream entirely divorced from hardware manufacturing, justifying a software-tier valuation multiple.

Tail risks

Catastrophic Cyber or AI Malfunction

Operational Efficiency

15% probabilityStock price impact: -35.0%Earnings impact: Not quantified

A critical software failure, cybersecurity breach, or artificial intelligence hallucination during a live procedure results in severe patient outcomes. This would prompt immediate regulatory suspensions, stalling the next-generation rollout, destroying the brand trust moat, and exposing the firm to catastrophic litigation and multi-billion-dollar repricing.

Antitrust Right-to-Repair Intervention

Regulatory

15% probabilityStock price impact: -30.0%Earnings impact: Not quantified

Regulators successfully appeal antitrust dismissals, legally mandating interoperability with third-party, low-cost generic instrument manufacturers. This would instantly destroy the closed-ecosystem razor-and-blades model, collapsing gross margins from their historical high levels to hardware-commodity levels and forcing a violent downward re-rating of the stock.

#6TSS logoTSS
TSSI:NASDAQHQ:Listed:

Information Technology · IT Consulting & Other Services

Data center infrastructure services company providing integration, deployment, and facilities services for high-performance computing environments.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

The shift to high-margin server assembly structurally improves profitability and boosts long-term earnings potential.

What to watch

A Primary oem contract termination could erode market share and pricing power.

+189.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
14.5x
59/100
28/100

Flagship insight

How This Hidden Liquid Cooling Integrator Is Exploiting The AI Hardware Bottleneck

A sharp divergence exists between the optical top-line revenue decline and underlying high-margin systems integration growth. While high customer concentration remains a primary risk, the transition to complex liquid-cooled rack assembly underpins a structural margin expansion, positioning this asset as a critical physical bottleneck in the data center buildout.

The company is shifting its business away from low-profit computer parts reselling toward high-profit assembly of liquid-cooled server racks for artificial intelligence data centers. While the stock market panicked over a recent drop in total sales, this drop was actually a planned move to focus on more profitable services. By using its newly expanded factory in Texas, the company can handle the massive demand for physical AI infrastructure. Although relying on one major customer and spending heavily on inventory create short-term challenges, the company's debt-free position provides a strong safety net.

  • The shift to high-margin server assembly structurally improves profitability and boosts long-term earnings potential.
  • The newly expanded Texas facility allows the company to handle much larger orders and lower its average operating costs.
  • Relying on a single major customer for almost all sales remains a major risk that could hurt future growth.
  • High inventory costs are temporarily draining cash, which could lead to a need for extra funding if delayed.
  • Global supply chain delays and part shortages could slow down assembly and delay sales recognition.
  • The stock looks cheap compared to other companies in the artificial intelligence infrastructure space, offering a great entry point for long-term investors.

Advisor consensus

The primary disagreement across reports centers on the durability and pricing power of the company's relationship with its primary OEM partner. Some reports adopt a highly cautious stance, arguing that the company is a commoditized, captive assembler operating at the mercy of its master, which will eventually squeeze margins. Conversely, more constructive reports highlight the strategic hiring of former top-tier OEM executives as forensic evidence of a deepening, secure partnership. There is also disagreement regarding the timeline for free cash flow inflection, with estimates split on how quickly the Georgetown facility can absorb fixed costs.

Risk and opportunity map

Longer-term opportunities

Tier-1 Customer Diversification Breakout

Competitive Positioning

30% probabilityStock price impact: +55.0%Earnings impact: Not quantified

The company successfully secures a direct, multi-year integration contract with a secondary Tier-1 OEM or a major hyperscaler. Breaking the single-customer monopoly would instantly validate the company's integration moat and eliminate the steep customer concentration discount. This structural derisking would attract a massive flood of institutional capital, driving immediate and violent multiple expansion as the addressable market dramatically widens.

Strategic Acquisition by OEM

Capital Allocation

25% probabilityStock price impact: +50.0%Earnings impact: Not quantified

A major server OEM or a large-cap data center infrastructure player decides to acquire the company outright to secure proprietary domestic liquid-cooling integration capacity. In a highly constrained global hardware market, buying the company's existing footprint, skilled labor, and operational capacity provides instant control over deployment schedules, commanding a substantial buyout premium over public market valuations.

Tail risks

Primary OEM Contract Termination

Competitive Positioning

20% probabilityStock price impact: -70.0%Earnings impact: Not quantified

The primary OEM partner decides to vertically internalize liquid-cooled rack assembly or shifts its integration volumes to a larger global competitor. Given the extreme customer concentration, this binary event would instantly evaporate the vast majority of the company's revenue base. The newly expanded Georgetown facility would immediately transform into a stranded, cash-burning liability, leading to catastrophic margin collapse and severe equity impairment.

AI Capex Reckoning and Bubble Deflation

Macroeconomic And Macrofinancial

25% probabilityStock price impact: -55.0%Earnings impact: Not quantified

Enterprise return on investment for generative AI applications fails to materialize, prompting hyperscalers to abruptly slash their massive capital expenditure budgets. A sudden freeze in data center expansion would dry up rack integration orders globally. Left with expanded fixed facility costs and a massive working capital buildup, the company's operating leverage would work violently in reverse, plunging it into deep operating losses.

The leading five

The Top 5

#5 → #1

Five ideas remain. Each passed the full editorial review and earned a place in this edition's highest-conviction group.

FLNC:NASDAQHQ:Listed:

Industrials · Electrical Components & Equipment

Energy storage technology company providing grid-scale battery systems, software, and services for utilities and renewable developers.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Strong backing from major industrial parent companies helps secure large contracts that smaller rivals cannot win.

What to watch

A Dilutive capital raise could tighten funding flexibility and force a dilutive capital raise.

+307.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
0.0x
28/100
20/100

Flagship insight

Why the AI Infrastructure Boom is Creating a Dangerous Working Capital Trap

There is sharp divergence across reports regarding whether massive grid-scale storage backlogs can overcome severe transpacific shipping bottlenecks and negative cash flows. While the primary driver remains inelastic hyperscaler data center demand, the ultimate risk centers on a potential working capital crunch and dilutive financing.

The company is currently caught in a tug-of-war between two powerful forces. On one side, the massive boom in artificial intelligence and data centers is creating an urgent, non-stop demand for large-scale battery storage systems to keep power grids stable. On the other side, the company is burning through cash to buy inventory and build these massive projects, leading to a negative cash flow of $271 million over the past year. While the company has a massive $5.6 billion backlog of orders, getting these batteries shipped and installed is difficult due to global shipping delays and new import taxes. If the company can survive this cash squeeze and sell more of its high-margin grid management software, it has a bright future.

  • Huge demand from AI data centers provides a massive, long-term pipeline of future orders.
  • High cash burn and heavy spending on inventory create a risky short-term financial squeeze.
  • Global shipping bottlenecks and import tariffs could delay project completions and revenue.
  • Intense competition from cheaper overseas battery manufacturers limits the company's pricing power.
  • Strong backing from major industrial parent companies helps secure large contracts that smaller rivals cannot win.
  • Everyday investors should watch for positive cash flow and rising software sales as signs of a healthy turnaround.

Advisor consensus

The primary disagreement across reports centers on the company's valuation multiple and near-term survival runway. Optimistic views frame the asset as a critical, mispriced AI infrastructure play trading at a deep discount to sales, arguing that the massive backlog and hyperscaler partnerships will rapidly drive positive cash flow. Conversely, skeptical perspectives emphasize the broken owner economics of a low-margin hardware assembler, warning that the severe free cash flow burn and rising debt levels will inevitably force highly dilutive equity financing before any software-driven margin expansion can materialize.

Risk and opportunity map

Longer-term opportunities

Direct Hyperscaler Prepayments and Funding

Capital Allocation

35% probabilityStock price impact: +50.0%Earnings impact: Not quantified

Desperate to secure grid-scale battery capacity for their AI data centers, major technology hyperscalers could bypass traditional utility procurement and directly contract with the company, providing massive upfront cash prepayments. This non-traditional funding would instantly resolve the company's working capital constraints, eliminate dilution risk, and trigger a rapid upward re-rating.

Next-Generation Chemistry Integration

Innovation And Product

25% probabilityStock price impact: +40.0%Earnings impact: Not quantified

The successful commercial integration of disruptive, non-lithium battery chemistries (such as sodium-ion or solid-state) into the company's modular platforms. This technological breakthrough would structurally decouple the company from lithium supply chain constraints and geopolitical tariffs, drastically lowering the levelized cost of storage and expanding the addressable market.

Tail risks

Forced Dilutive Capital Raise

Capital Allocation

40% probabilityStock price impact: -50.0%Earnings impact: Not quantified

If the company's severe free cash flow burn persists and revenue recognition is delayed by supply chain disruptions, the remaining liquidity buffer will be rapidly exhausted. Under restrictive credit conditions, the company would be forced to execute a highly dilutive secondary equity offering at depressed valuations, permanently impairing per-share intrinsic value.

Predatory Pricing War

Competitive Positioning

30% probabilityStock price impact: -40.0%Earnings impact: Not quantified

A vertically integrated competitor, leveraging massive manufacturing scale and a robust balance sheet, initiates a predatory pricing war in grid-scale storage to capture market share. Lacking captive cell manufacturing, the company would be forced to match prices, driving gross margins back into single digits and structurally breaking its path to profitability.

BEAM:NASDAQHQ:Listed:

Health Care · Biotechnology

Beam Therapeutics Inc., a biotechnology company, engages in the development of precision genetic medicines for patients suffering from serious diseases in the United States.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

New government rules favoring domestic biotechnology companies provide a strong competitive advantage for US-based operations.

What to watch

An Off-target genotoxicity event could trigger clinical holds and undermine confidence in the treatment platform.

+298.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
0.0x
55/100
27/100

Flagship insight

How Systemic In Vivo Gene Editing Will Redefine Future Biotech Valuations

High consensus exists that the investment thesis hinges on transitioning from ex vivo cell therapies to scalable in vivo platforms. While near term commercial launches face intense competitive friction and cash burn, a robust capital runway provides a critical survival bridge through a restrictive macroeconomic regime.

The company is moving from complex, personalized cell treatments done outside the body to simpler, direct gene-editing treatments delivered inside the body. While the first approved treatments for sickle cell disease will face tough competition and slow adoption due to complicated hospital procedures, the real long-term value lies in direct liver treatments. Thanks to a massive cash reserve and smart financing deals, the company has enough money to survive several years without needing to raise expensive new capital in today's high-interest-rate environment, allowing its advanced technology to prove itself.

  • Direct treatments inside the body are much easier to scale and could eventually reach a far larger patient population.
  • A massive cash cushion protects the company from being forced to issue new stock at low prices during market downturns.
  • The first commercial launch will be expensive and slow, which may temporarily hurt financial results and investor sentiment.
  • Owning the core patents for advanced gene editing makes the company a highly attractive target for larger pharmaceutical partners.
  • New government rules favoring domestic biotechnology companies provide a strong competitive advantage for US-based operations.
  • The main risks are unexpected safety issues in clinical trials and potential delays in setting up specialized manufacturing facilities.

Advisor consensus

The primary disagreements across the reports center on the commercial viability and strategic focus of the lead ex-vivo sickle cell program versus the in-vivo liver platform. Some perspectives view the ex-vivo launch as a necessary clinical validation step that will eventually secure meaningful market share, while others dismiss it as a high-cost, low-ROI distraction that will severely drag on near-term earnings. Additionally, there is divergence regarding the timing and necessity of future capital raises, with some models predicting inevitable dilution by 2028 and others arguing that non-dilutive milestone payments will fully bridge the gap to commercialization.

Risk and opportunity map

Longer-term opportunities

Strategic Mega-Cap Pharma Acquisition

Competitive Positioning

30% probabilityStock price impact: +75.0%Earnings impact: Not quantified

A major pharmaceutical conglomerate facing severe patent cliffs and seeking next-generation genomic infrastructure launches a friendly or hostile takeover. Driven by the scarcity of validated, single-dose curative platforms, the acquirer pays a massive premium to internalize the company's foundational base-editing intellectual property and AI-driven guide RNA engine, realizing decades of future cash flows instantly.

Accelerated Biomarker-Driven Regulatory Approval

Regulatory

35% probabilityStock price impact: +55.0%Earnings impact: Not quantified

Highly positive interim clinical data prompts the FDA to grant accelerated approval for the in-vivo liver program based on surrogate biomarker endpoints rather than requiring years of long-term clinical outcomes. This regulatory victory pulls forward commercial revenues by years, instantly re-rates the entire platform, and lowers the capitalized cost of clinical development.

Tail risks

Catastrophic Off-Target Genotoxicity Event

Innovation And Product

15% probabilityStock price impact: -75.0%Earnings impact: Not quantified

A patient in a late-stage clinical trial develops a severe malignancy or experiences a fatal adverse event directly linked to off-target editing or lipid nanoparticle toxicity. The FDA immediately imposes a blanket clinical hold, shattering the platform's core safety thesis, halting clinical trials globally, and triggering a massive, permanent loss of institutional confidence.

Capital Runway Exhaustion and Distressed Dilution

Capital Allocation

25% probabilityStock price impact: -45.0%Earnings impact: Not quantified

Severe clinical delays, commercial launch failures, or restrictive financing covenants rapidly deplete the company's cash reserves during a broader macroeconomic credit freeze. Forced to execute a highly toxic secondary offering at a massive discount to keep the wet labs running, existing shareholders suffer permanent, severe equity dilution and loss of capital.

The finalists

The Top 3

#3 → #1

The shortlist is over. These three stocks earned the strongest conviction in this edition. Count down to the research team's number-one pick.

NXT:NASDAQHQ:Listed:

Industrials · Electrical Components & Equipment

Solar technology company supplying smart tracking systems, software, and energy yield optimization for utility-scale solar projects.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Smart software upgrades turn simple steel solar trackers into high-margin, recurring revenue streams.

What to watch

A Repeal of advanced manufacturing subsidies could remove an important margin benefit and weaken domestic production economics.

+151.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
22.1x
68/100
62/100

Flagship insight

Why the Market Misprices This Critical Infrastructure Node Powering Artificial Intelligence

There is high consensus that this asset-light solar tracking leader is transitioning into a high-margin software and energy storage platform. While grid interconnection queues present near-term friction, explosive artificial intelligence power demand and localized supply chains insulate its massive backlog from global trade disruptions.

This company is a leading player in the solar energy sector, acting as a vital link between solar power plants and the massive energy needs of artificial intelligence data centers. While the general public often views solar as a volatile industry dependent on government subsidies, this business stands out due to its unique software and smart design. It helps solar panels capture more sunlight and operates with an incredibly light manufacturing footprint. Even though high interest rates and power grid delays are slowing down some projects, the massive demand for electricity to power AI ensures a steady stream of future business.

  • Smart software upgrades turn simple steel solar trackers into high-margin, recurring revenue streams.
  • A fortress balance sheet with zero debt protects the company from high interest rates and allows it to buy out struggling competitors.
  • Localized US manufacturing shields the company from expensive global shipping blockades and heavy import tariffs.
  • Delays in connecting new solar projects to the electrical grid remain the biggest obstacle to short-term revenue growth.
  • Expanding into battery storage systems allows the company to sell complete power solutions directly to big tech firms.
  • The stock price may experience short-term volatility as the market adjusts from speculative hype to realistic growth expectations.

Advisor consensus

The primary disagreement across the reports centers on the near-term trajectory of the company's valuation multiple and margin sustainability. Some perspectives argue that the current multiple is highly vulnerable to immediate compression as grid bottlenecks delay backlog conversion, advising caution until a valuation reset occurs. Conversely, other views maintain that the software-driven margin expansion and inelastic demand from artificial intelligence data centers fully justify the premium multiple, suggesting that any near-term pullbacks represent aggressive accumulation opportunities. These differences stem from varying assumptions regarding the speed of software integration and the severity of interest rate headwinds.

Risk and opportunity map

Longer-term opportunities

Hyperscaler Direct Procurement Consortium

Competitive Positioning

35% probabilityStock price impact: +30.0%Earnings impact: Not quantified

Mega-cap technology firms bypass traditional utilities to directly fund and build dedicated, off-grid solar-plus-storage microgrids for their massive data centers. If the company is selected as the exclusive tracking and storage standard for this consortium, it would unlock rate-insensitive, multi-billion-dollar direct procurement pipelines, bypassing grid bottlenecks and driving a massive valuation re-rating.

Distressed Competitor Consolidation

Capital Allocation

40% probabilityStock price impact: +15.0%Earnings impact: Not quantified

The combination of high interest rates and global shipping chaos bankrupts undercapitalized tier-two tracker competitors. Armed with substantial cash reserves and zero debt, the company executes highly accretive acquisitions of distressed rivals' intellectual property and market share at fire-sale valuations, permanently consolidating the utility-scale tracker market into a highly profitable oligopoly.

Tail risks

Repeal of Advanced Manufacturing Subsidies

Regulatory

25% probabilityStock price impact: -30.0%Earnings impact: Not quantified

A shifting political landscape leads to the complete legislative repeal of clean energy tax credits, including the advanced manufacturing tax credits that currently pad the company's gross margins. Losing these subsidies would instantly strip significant basis points from baseline profitability, rendering domestic manufacturing a cost liability and forcing severe margin compression.

AI Capital Expenditure Collapse

Sector And Industry

20% probabilityStock price impact: -25.0%Earnings impact: Not quantified

If the enterprise return on investment for generative artificial intelligence pilots fails to materialize, hyperscalers may abruptly halt their massive capital expenditure loops. A sudden cancellation of gigawatt-scale power purchase agreements would cause the company's celebrated backlog to evaporate, leaving newly expanded domestic manufacturing capacity underutilized and severely damaging cash flow.

PINS:NYSEHQ:Listed:

Communication Services · Interactive Media & Services

Visual discovery platform helping people find inspiration and ideas for lifestyle projects through image-based social media.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Revenue grew 18% while record users and more than $2 billion of buybacks reinforce monetization and per-share value creation.

What to watch

Watch whether international monetization and advertiser returns keep improving as AI shopping tools compete for discovery traffic and privacy rules tighten.

+149.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
49.1x
74/100
54/100

Flagship insight

How Aggressive Capital Cannibalization Is Quietly Restructuring Visual Commerce Economics

There is high consensus that aggressive capital return programs and outsourced cloud infrastructure are structurally insulating this visual commerce platform from macroeconomic headwinds. While retail advertising spend faces cyclical pressure, the mechanical compounding of per-share metrics through float contraction remains the primary driver of long-term valuation expansion.

This visual discovery platform is changing from a simple social media site into a highly profitable shopping tool. Even though inflation and high interest rates are forcing retail brands to cut back on advertising, the company is in a very strong position. Instead of spending billions of dollars building expensive computer servers for artificial intelligence, it is renting technology from partners. This smart move saves massive amounts of cash, which management is using to buy back and retire its own stock. As the number of shares shrinks, each remaining share becomes much more valuable.

  • Massive stock buybacks are rapidly reducing the number of shares, making each remaining share worth more.
  • Renting artificial intelligence technology from partners keeps spending low and protects cash reserves.
  • New shopping features make it easier for users to buy products directly, attracting more advertisers.
  • The company has almost zero debt, making it safe from high interest rates and economic downturns.
  • A major risk is that new artificial intelligence search tools could let users shop without visiting the platform.
  • Experts disagree on whether the company can successfully grow its advertising revenue outside of North America.

Advisor consensus

The primary disagreements across the reports center on the long-term margin ceiling and the structural impact of the cloud infrastructure commitments. Some perspectives view the multi-billion-dollar cloud contract as a highly strategic, capital-light maneuver that protects free cash flow, while others caution that it represents a rigid, long-term operational tollbooth that could compress margins if revenue growth decelerates. Additionally, there is divergence regarding the threat of generative artificial intelligence, with some viewing it as an existential disintermediation risk and others seeing it as a lucrative data-licensing opportunity.

Risk and opportunity map

Longer-term opportunities

Strategic Megacap Acquisition

Competitive Positioning

20% probabilityStock price impact: +45.0%Earnings impact: Not quantified

Given the platform's highly unique, human-curated visual intent dataset and compressed enterprise value, a mega-cap technology or e-commerce giant could launch a buyout. Acquiring this proprietary data graph would provide a massive strategic advantage in the AI commerce wars, triggering an immediate premium re-rating.

Exclusive AI Data Licensing

Innovation And Product

30% probabilityStock price impact: +30.0%Earnings impact: Not quantified

The company could establish high-margin data licensing agreements with frontier artificial intelligence labs seeking clean, intent-driven visual training data. Erecting a tollbooth around its unique visual taxonomy would create a recurring revenue stream with zero marginal cost, structurally shifting the platform's valuation multiple.

Tail risks

Agentic AI Search Disintermediation

Competitive Positioning

25% probabilityStock price impact: -45.0%Earnings impact: Not quantified

The rapid deployment of multimodal, autonomous AI assistants could allow consumers to generate, curate, and purchase aesthetic designs directly within conversational interfaces. If users bypass discrete apps entirely, the platform's core discovery moat and user engagement would suffer a structural collapse.

Draconian Privacy Framework Lockout

Regulatory

20% probabilityStock price impact: -35.0%Earnings impact: Not quantified

Coordinated global regulatory updates to data privacy frameworks could completely sever third-party conversion tracking. Stripped of the ability to prove return on ad spend to retail partners, the platform's ad targeting would go blind, sparking immediate customer churn and a collapse in free cash flow.

The winner

The Number-One Pick

The edition's highest-conviction selection, combining near-term opportunity with long-term confirmation.

TTD:NASDAQHQ:Listed:

Communication Services · Advertising

Technology platform for buyers of advertising enabling data-driven digital advertising campaigns across channels.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

The company's cookie-free tracking technology has become an essential, un-displaceable tool for the open internet.

What to watch

An Universal browser identity blockade could weaken targeting and attribution, pushing advertisers toward walled gardens.

+306.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
16.7x
65/100
36/100

Flagship insight

Why the Market Misunderstands the Structural Shift in Programmatic Advertising Moats

There is high consensus that structural shifts in Connected TV and Retail Media networks insulate this asset from broader macroeconomic headwinds. While short-term ad-spend compression acts as a cyclical friction, aggressive capital allocation and identity infrastructure adoption provide a robust long-term margin of safety.

This company is shifting from a fast-growing tech favorite to a highly profitable cash machine. Even though high inflation and global economic worries are causing brands to temporarily cut back on their marketing budgets, the long-term shift toward streaming television and online shopping ads remains incredibly strong. The company's unique tracking technology has become the industry standard, helping advertisers target audiences safely without relying on traditional web cookies. By using its strong cash flow to buy back its own cheap stock, the company is quietly boosting its value per share, creating a strong safety net for patient investors while waiting for the broader economy to recover.

  • Streaming television ads continue to grow rapidly as traditional cable TV declines, providing a steady source of revenue.
  • The company's cookie-free tracking technology has become an essential, un-displaceable tool for the open internet.
  • Massive stock buybacks are reducing the number of outstanding shares, making each remaining share more valuable over time.
  • Government antitrust lawsuits against tech giants could open up massive new market share opportunities for independent platforms.
  • Main risks include a deeper economic recession that forces brands to cut advertising budgets even further in the near term.
  • Investors should watch the company's cash flow and profit margins to confirm the business remains healthy and resilient.

Advisor consensus

The primary disagreements across reports center on the expected timeline for macroeconomic recovery and the severity of competitive threats. Some perspectives emphasize immediate risks from Amazon's aggressive pricing and C-suite governance transitions, advocating for a cautious near-term outlook. Conversely, other views focus on the unassailable nature of the company's identity moat and the mathematical inevitability of share buybacks, projecting a rapid upward repricing. These differences stem from varying assumptions regarding the speed of direct-to-brand migration and the rate of Connected TV ad-tier adoption.

Risk and opportunity map

Longer-term opportunities

Google Ad Manager Forced Divestiture

Regulatory

35% probabilityStock price impact: +45.0%Earnings impact: Not quantified

A binding federal court ruling forcing the structural breakup of Google's ad-tech stack would instantly dismantle the dominant walled garden. Premium publisher inventory would flood into neutral exchanges, allowing the company's OpenPath technology to capture massive market share overnight and permanently re-rating the asset as a global utility.

Exclusive AI Search Monetization Partnership

Innovation And Product

25% probabilityStock price impact: +35.0%Earnings impact: Not quantified

Securing an exclusive partnership to power programmatic ad placement for a leading generative AI search platform would fuse the company's identity graph with next-generation web traffic. This would unlock an entirely new, high-margin revenue vector, completely neutralizing the AI-disruption narrative and driving massive multiple expansion.

Tail risks

Universal Browser Identity Blockade

Regulatory

20% probabilityStock price impact: -45.0%Earnings impact: Not quantified

Major operating system and browser developers could collude to block all hashed email and alternative identifier frameworks, including Unified ID 2.0, at the hardware level under the guise of privacy. This structural blockade would severely degrade targeting and attribution efficacy, forcing advertisers back into walled gardens and permanently impairing margins.

Coordinated Agency Boycott Contagion

Competitive Positioning

25% probabilityStock price impact: -35.0%Earnings impact: Not quantified

If legacy advertising holding companies form a coordinated cartel to boycott the platform in response to direct-to-brand disintermediation, the company's pristine customer retention rate could crack. This would lead to an absolute contraction in gross spend and revenue, severely damaging the cash-flow profile before direct brand relationships can fully mature.

Market context and selection approach

Markets remain selective, so this review emphasizes earnings delivery, competitive position, capital needs, and the next operating milestones. Current evidence can support a thesis while still leaving meaningful company, policy, liquidity, or macro risk.

The list favors the strongest eligible assets and excludes any name whose current evidence no longer supports its investment case. It never adds a weaker asset simply to make the list longer.

References

Frozen links are separated into editorial-review evidence, 5–6 global-context references, and 3–4 governed Researcher citations per selected asset. Duplicate URLs appear once; the combined citation list is capped at 30.

A. Editorial-review sources

  1. 1.The Trade Desk Reports Second Quarter 2026 Financial Results The Trade Desk, Inc. · ISSUER FILING · 6 Aug 2026, 00:00 UTChttps://www.sec.gov/Archives/edgar/data/1671933/000167193326000085/ttd-20260806x8kexx991.htmReviewed for: The Trade Desk, Inc. (TTD.NASDAQ)
  2. 2.Pinterest Announces Second Quarter 2026 Results, Delivers 18% Revenue Growth and Record Users Pinterest, Inc. / U.S. Securities and Exchange Commission · ISSUER FILING · 4 Aug 2026, 00:00 UTChttps://www.sec.gov/Archives/edgar/data/1506293/000150629326000102/q2-26xpressrelease.htmReviewed for: Pinterest, Inc. (PINS.NYSE)
  3. 3.Nextpower Reports Q1 Fiscal Year 2027 Financial Results Nextpower Inc. · ISSUER RELEASE · 30 Jul 2026, 00:00 UTChttps://investors.nextracker.com/news/news-details/2026/Nextpower-Reports-Q1-Fiscal-Year-2027-Financial-Results/default.aspxReviewed for: Nextracker Inc. (NXT.NASDAQ)
  4. 4.Beam Therapeutics Reports Second Quarter 2026 Financial Results and Business Updates Beam Therapeutics Inc. · ISSUER FILING · 4 Aug 2026, 00:00 UTChttps://www.sec.gov/Archives/edgar/data/1745999/000119312526331522/beam-20260804.htmReviewed for: Beam TherapeuticsInc (BEAM.NASDAQ)
  5. 5.Fluence Energy Reports Third Fiscal Quarter 2026 Results Fluence Energy, Inc. · ISSUER RELEASE · 5 Aug 2026, 00:00 UTChttps://ir.fluenceenergy.com/news-releases/news-release-details/fluence-energy-inc-reports-third-fiscal-quarter-2026-resultsReviewed for: Fluence Energy Inc (FLNC.NASDAQ)
  6. 6.TSS Reports Second Quarter 2026 Financial Results TSS, Inc. · ISSUER RELEASE · 13 Aug 2026, 00:00 UTChttps://ir.tssiusa.com/tss-reports-second-quarter-2026-financial-results/Reviewed for: TSS Inc. (TSSI.NASDAQ)
  7. 7.Intuitive Announces Second Quarter 2026 Earnings Intuitive Surgical, Inc. · ISSUER RELEASE · 16 Jul 2026, 00:00 UTChttps://isrg.intuitive.com/press-releasesReviewed for: Intuitive Surgical, Inc. (ISRG.NASDAQ)
  8. 8.Humacyte Announces Second Quarter 2026 Financial Results and Business Update Humacyte, Inc. · ISSUER RELEASE · 12 Aug 2026, 00:00 UTChttps://investors.humacyte.com/news-releases/news-release-details/humacyte-announces-second-quarter-2026-financial-results-and/Reviewed for: Humacyte Inc (HUMA.NASDAQ)
  9. 9.IBM Releases Second-Quarter Results IBM · ISSUER RELEASE · 22 Jul 2026, 00:00 UTChttps://newsroom.ibm.com/2026-07-22-IBM-RELEASES-SECOND-QUARTER-RESULTSReviewed for: International Business Machines Corporation (IBM.NYSE)
  10. 10.UnitedHealth Group Reports Second Quarter 2026 Results UnitedHealth Group · ISSUER RELEASE · 16 Jul 2026, 00:00 UTChttps://www.unitedhealthgroup.com/newsroom/2026/2026-07-16-uhg-reports-second-quarter-2026-results.htmlReviewed for: UnitedHealth Group Incorporated (UNH.NYSE)

B. Global market context

These dated files capture broader market, macroeconomic, policy, and cross-asset context. Each frozen file is supplied as input to every advisor model during deep analysis; its citations never count toward an asset-specific minimum.

This legacy draft has no governed global-context references. Rematerialization is required before approval.

C. Asset-specific deep-analysis sources

Captured by governed AI Researcher agents. Shared URLs are shown once and identify every selected asset they support.

This legacy draft has no governed asset-specific URLs. Fresh Researcher evidence and rematerialization are required before approval.

Important information

Research scope and investor notice

Research scope

  • The post-cutoff source state is NOT_RETAINED where no newer primary-source document was available; retained official sources were reused without inventing citations.
  • This editorial review does not rerun forecasts or guarantee that every fast-moving company, policy, protocol, market, or geopolitical development has been captured.

Investor notice

AI-assisted editorial analysis. Reviewed and approved by Russlan Ramdowar. Published by Future Edge Group FZE. This is general research, not personalized investment advice.

Forecasts, ratings, and return estimates are uncertain and may change as new evidence becomes available.