Assets

iPulse AI Editorial Picks research

Best Non-US Stocks to Buy Now

Explore standout stocks across Europe, Asia and other global markets spanning 22 non-US countries, including China, Germany, India, France, the United Kingdom, South Korea and Singapore. iPulse AI's independent agentic investment research combines one-year return potential with five-year trend confirmation, multi-agent consensus, business quality, financial health, valuation and risk resilience. Every selection includes a clear investment thesis, projected returns, catalysts and the risks that could change the outlook.

Editorial ApproverRusslan Ramdowar iPulse AI Engine V6 15 min read
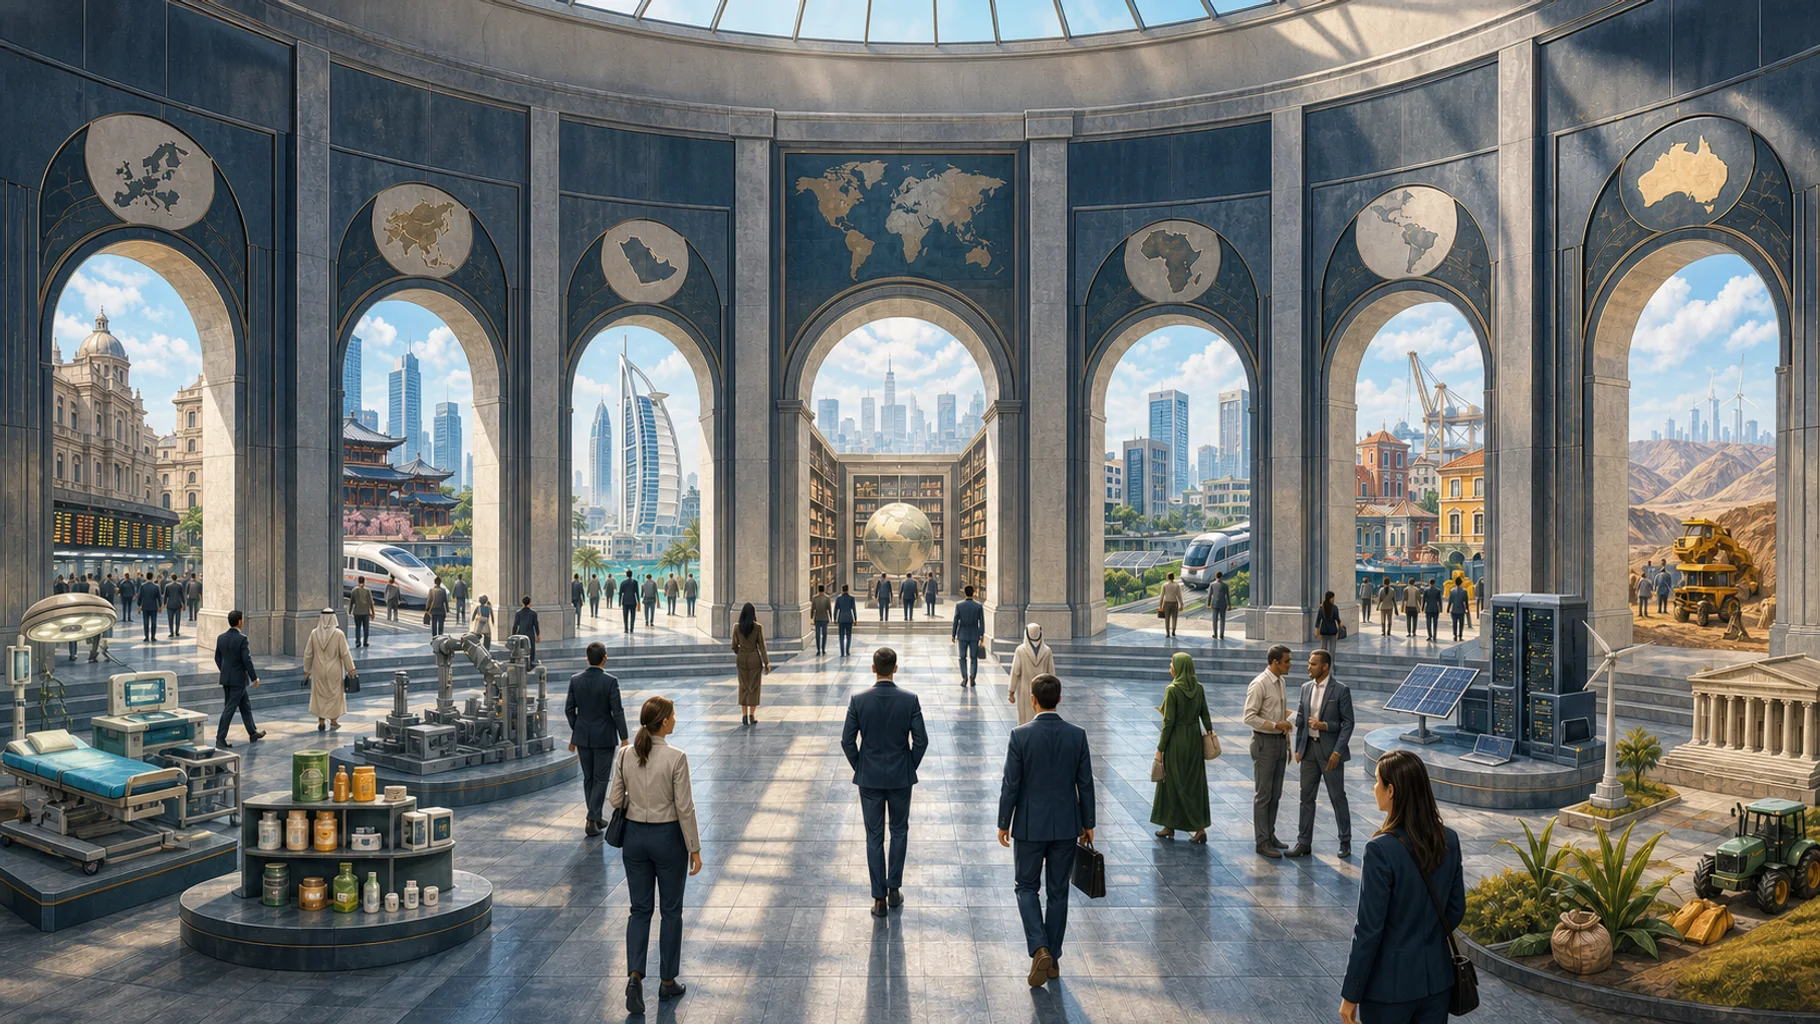
Investment professionals compare six brightly lit regional business windows spanning Europe, Asia, the Middle East, Africa, Latin America, and Oceania.

Our Approach: Our research starts with about 100,000 stocks. For this edition, 376 assets passed preselection and underwent deep multi-agent analysis. iPulse AI Engine V6 ranked the top 10, and 10 Editorial Top Picks passed the separate evidence review and approval workflow. Read the detailed methodology

Editorial Picks countdown

Top 10 Editorial Picks

9868:HKEXHQ:Listed:

Consumer Discretionary · Automobile Manufacturers

XPeng Inc. designs, develops, manufactures, and markets smart electric vehicles (EVs) in the People's Republic of China.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Software licensing deals bring in high-profit revenue without the heavy costs of building physical cars.

What to watch

A Sovereign AI hard fencing ban could limit overseas software growth and materially shrink the addressable market.

+211.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
0.0x
39/100
27/100

Flagship insight

How High Margin Software Licensing Is Quietly Transforming Automotive Platform Economics

High consensus across reports indicates a structural transition from hardware manufacturing to high-margin software licensing, driven by strategic partnerships and autonomous architecture. While domestic price wars and Western tariffs present severe frictions, the asset-light IP monetization model establishes a robust, self-funding path toward long-term profitability.

The company is changing from a basic electric car maker into a smart technology business that licenses its software to other automakers. While most investors only look at monthly car sales and worry about price wars in China, the real story is the high-profit software and technology fees the company is starting to collect. By partnering with major global car brands, the company can make money without the high costs of building new factories. This shift is supported by their advanced self-driving software and custom computer chips, which help lower manufacturing costs and make their cars more appealing to tech-savvy buyers.

  • Software licensing deals bring in high-profit revenue without the heavy costs of building physical cars.
  • Custom self-driving chips and software help lower the cost of making each vehicle, boosting overall margins.
  • Partnerships with major global brands provide extra cash, validate the technology, and help lower supply chain costs.
  • High tariffs in the US and Europe limit direct exports, forcing the company to assemble cars locally in those regions.
  • Fierce competition and price cuts in China keep constant pressure on car profit margins, requiring high software sales to offset.
  • Turning cash-flow positive helps the company survive tough economic times without needing to borrow expensive money or issue new stock.

Advisor consensus

The primary disagreement across reports centers on the long-term viability of the hardware manufacturing segment versus the software licensing model. Some analysts argue that the hardware business is a structurally flawed, capital-heavy drag that will permanently depress returns due to relentless domestic price wars. Conversely, others view hardware deliveries as a necessary, break-even data-harvesting tool designed to feed the high-margin autonomous driving neural network. There is also divergence regarding the speed and capital efficiency of localized European assembly strategies to bypass tariffs.

Risk and opportunity map

Longer-term opportunities

Global Platform Standardization

Competitive Positioning

30% probabilityStock price impact: +55.0%Earnings impact: Not quantified

If additional major legacy global automakers capitulate on internal software development and license the company's electronic architecture, it would validate the platform as a universal autonomous operating system. This event would trigger a massive multiple expansion, transitioning the business into a pure-play, high-margin technology vendor with infinite scalability and minimal physical capital requirements.

Commercial Robotaxi Fleet Scale

Innovation And Product

25% probabilityStock price impact: +50.0%Earnings impact: Not quantified

Securing regulatory approval for fully autonomous, driverless robotaxi operations in top-tier Chinese cities would fundamentally alter the business model. Shifting from one-off vehicle sales to recurring mobility-as-a-service revenue would bypass human labor costs and capture immense lifetime value per vehicle, triggering an explosive upward re-rating of the equity.

Tail risks

Sovereign AI Hard-Fencing Ban

Regulatory

25% probabilityStock price impact: -50.0%Earnings impact: Not quantified

Western regulators could implement complete bans on Chinese-developed autonomous driving software and connected-vehicle operating systems due to national security concerns. This geopolitical blockade would trap the company's advanced technology entirely within domestic and allied emerging markets, permanently halving its future total addressable market and crushing the global software licensing thesis.

Advanced AI Chip & Foundry Blockade

Political And Geopolitical

20% probabilityStock price impact: -45.0%Earnings impact: Not quantified

An escalation in geopolitical tensions could lead to a total blockade of advanced semiconductor foundries or severe restrictions on cloud compute access. Stripped of the advanced silicon required to train next-generation autonomous models, the company's technological edge would rapidly degrade, forcing a reversion to low-margin hardware manufacturing.
9999:HKEXHQ:Listed:

Information Technology · Internet Services & Infrastructure

NetEase, Inc. engages in online games, music streaming, online intelligent learning services, and internet content services businesses in China and internationally.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Higher game revenue, lower revenue-sharing costs, and a larger net-cash position reinforce resilient, capital-light economics.

What to watch

Watch whether heavier research, marketing, and tax costs continue to pressure profit despite stronger game revenue and a growing cash balance.

+114.0%
Excl. dividends: +90.5%
2.3%Dividend yield (net)
0.0%Buyback yield
16.6x
79/100
64/100

Flagship insight

The Underappreciated Digital Toll Bridge Yielding Massive Cash in Volatile Markets

There is high consensus across reports that this digital entertainment asset represents a premier capital-light compounding vehicle. While geopolitical overhang and domestic regulatory fears depress the valuation multiple, the primary driver remains structural AI-enabled cost deflation, while the main risk centers on potential domestic monetization caps.

This company is a highly profitable digital entertainment giant that is currently being ignored because of general worries about the Chinese economy and government regulations. In reality, the business is a cash-printing machine with a massive cash reserve and virtually no debt. It makes popular online games where players spend a lot of time and money, creating a steady stream of income. By using new artificial intelligence tools, the company is making games much cheaper and faster, which will boost profits even if overall sales growth slows down.

  • Massive cash reserves and almost zero debt make the company incredibly safe from economic downturns.
  • New artificial intelligence tools are cutting the cost of making games, leading to higher profit margins.
  • Online games are cheap entertainment, meaning players keep spending even during tough economic times.
  • The company is actively buying back its own shares, which naturally increases the value for remaining investors.
  • Upcoming access to mainland Chinese investors will bring fresh buying power to the stock.
  • Expanding into global markets with major new games reduces the company's reliance on any single country.

Advisor consensus

The primary disagreements across the reports center on the timeline and magnitude of artificial intelligence integration benefits and the success rate of global expansion. Some views project an immediate, dramatic margin expansion as generative AI automates development, while others project escalating compute inference costs and competitive pressure. Additionally, there is divergence regarding the valuation multiple; some expect a structural re-rating to global peer levels via Stock Connect, while others argue that persistent regulatory risk will permanently cap the multiple.

Risk and opportunity map

Longer-term opportunities

Global AAA Franchise Breakout

Innovation And Product

35% probabilityStock price impact: +25.0%Earnings impact: Not quantified

The successful launch of a globally dominant, multi-platform franchise in Western and Japanese markets would fundamentally alter the company's narrative. Achieving massive ex-China penetration would prove its capability as a global intellectual property powerhouse, diversifying revenue away from domestic regulatory risks and triggering an immediate upward re-rating to premium global peer multiples.

Outsized Special Capital Return

Capital Allocation

30% probabilityStock price impact: +20.0%Earnings impact: Not quantified

Given the massive net cash hoard and negligible debt, management could declare an extraordinary, one-time special dividend or double its share buyback program. This aggressive capital return would instantly close the alpha gap by transferring undeniable intrinsic value to shareholders, punishing short-sellers and forcing skeptical foreign investors to acknowledge the tangibility of the company's cash reserves.

Tail risks

Draconian Monetization Ban Legislation

Regulatory

20% probabilityStock price impact: -35.0%Earnings impact: Not quantified

A sudden, sweeping legislative ban on core gaming monetization mechanics within the domestic market, such as outlawing probabilistic gacha systems or daily login rewards, would instantly impair the company's earning power. This regulatory shock would permanently dismantle the unit economics of its most profitable titles, collapsing margins and forcing a severe downward reset of intrinsic value.

Geopolitical Conflict and Capital Freeze

Political And Geopolitical

15% probabilityStock price impact: -50.0%Earnings impact: Not quantified

A severe escalation of geopolitical tensions, such as kinetic action in the Taiwan Strait, could trigger sweeping international sanctions and capital controls. This would result in forced divestment by Western institutional funds, delisting from major exchanges, and the freezing of offshore dividend repatriation, causing a catastrophic liquidity vacuum and severe price impairment regardless of fundamental strength.

NOV:XETRAHQ:Listed:

Health Care · Biotechnology

Novo Nordisk A/S, together with its subsidiaries, engages in the research and development, manufacture, and distribution of pharmaceutical products.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

A debt-free balance sheet keeps the company incredibly safe from rising interest rates and global economic downturns.

What to watch

An Early US patent invalidation could accelerate generic competition and weaken the cash flow supporting investment and shareholder returns.

+138.0%
Excl. dividends: +128.0%
0.9%Dividend yield (net)
0.0%Buyback yield
11.4x
51/100
44/100

Flagship insight

How A Massive Volume Shift Is Rewriting The Metabolic Monopoly Thesis

High consensus across reports indicates that this metabolic giant is undergoing a structural transition from a high-margin specialty model to a high-volume utility framework. While regulatory price caps and competitive oral launches present near-term margin friction, massive global volume expansion and an unassailable manufacturing moat secure long-term cash flows.

The company is changing how it sells its popular weight-loss and diabetes treatments. It is moving away from expensive, hard-to-make injections toward easy-to-take daily pills. While this shift means the company will make less profit on each individual sale due to government price limits and new competition, it will allow them to sell to millions of new customers worldwide who could not afford or access the injections before. This massive increase in sales volume is expected to keep overall profits strong. The stock has fallen too far because investors are overly focused on lower prices rather than the huge wave of new customers.

  • Selling daily pills instead of injections makes the treatment much easier to distribute and use, dramatically expanding the customer base.
  • Heavy spending on new factories is finally ending, which will soon free up massive amounts of cash for the company.
  • Government price caps actually protect the company by making it too expensive for smaller, newer rivals to compete.
  • New medical approvals prove these treatments prevent heart attacks and kidney disease, forcing insurance companies to cover them.
  • A debt-free balance sheet keeps the company incredibly safe from rising interest rates and global economic downturns.
  • Main risks include intense competition from other major drugmakers and potential long-term side effects from widespread use.

Advisor consensus

The primary disagreements across reports center on the trajectory of margin compression and the competitive threat of rival oral formulations. Some analyses project a severe, permanent operating margin decline to the low-30s due to aggressive US price caps and direct competition. Conversely, other reports argue that manufacturing efficiencies, SG&A leverage, and massive volume scaling will stabilize margins in the high-30s. Additionally, there is disagreement regarding the timing of the free cash flow inflection, with estimates split on how quickly peaking capital expenditures will transition into cash-flow harvesting.

Risk and opportunity map

Longer-term opportunities

Next-Gen Pipeline Efficacy Breakthrough

Innovation And Product

35% probabilityStock price impact: +30.0%Earnings impact: Not quantified

If next-generation combination therapies or oral co-agonists demonstrate clinical weight-loss efficacy exceeding twenty-five percent with superior tolerability, the firm will reclaim unquestioned scientific leadership. This would allow the company to bypass regulatory price caps by establishing a premium-priced therapeutic tier, triggering massive multiple expansion.

Universal Sovereign Healthcare Mandates

Regulatory

30% probabilityStock price impact: +25.0%Earnings impact: Not quantified

Major national healthcare systems, facing unsustainable long-term costs from metabolic diseases, could mandate universal coverage for preventative metabolic therapies. This policy shift would instantly convert a partially discretionary market into a fully subsidized public utility, triggering an unprecedented acceleration in global volume.

Tail risks

Early US Patent Invalidation

Regulatory

20% probabilityStock price impact: -35.0%Earnings impact: Not quantified

If generic challengers successfully invalidate core US patents prior to their expected 2030 expiration, cheap generic alternatives would enter the market prematurely. This would collapse the firm's highest-margin profit pool, forcing a catastrophic downward revision of free cash flow, dividend coverage, and long-term valuation models.

Severe Long-Term Safety Signal

Innovation And Product

12% probabilityStock price impact: -45.0%Earnings impact: Not quantified

The emergence of a severe, delayed safety signal, such as rare oncological or severe gastrointestinal complications across the mass-medicated global population, would trigger immediate regulatory restrictions or recalls. This would destroy consumer trust, spark massive litigation liabilities, and permanently impair the franchise's terminal value.

#7UCB logoUCB
UCB:BRUHQ:Listed:

Health Care · Pharmaceuticals

UCB SA, a biopharmaceutical company, develops products and solutions for people with neurology and immunology diseases worldwide.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Rapid sales growth of its leading skin-treatment drug is driving the company's overall financial success and market share gains.

What to watch

A Post marketing safety signal emergence could undermine product adoption and expected growth.

+107.0%
Excl. dividends: +102.0%
0.5%Dividend yield (net)
0.0%Buyback yield
11.3x
55/100
90/100

Flagship insight

Unlevered Immunology Leader Set to Outperform Amid Global Stagflation and Rate Pressures

High consensus exists regarding the asset's transition into a self-funding immunology powerhouse, insulated from macroeconomic shocks by its unlevered balance sheet. While US pricing regulations and legacy patent cliffs present structural frictions, the rapid global scaling of its blockbuster immunology portfolio remains the primary driver of long-term value.

The company is successfully shifting from older brain-health drugs to highly profitable new skin and immune-system treatments. This change is generating massive amounts of cash, allowing the business to grow without needing to borrow expensive money. While older drugs are losing patent protection and US government rules may limit drug prices, the company's strong financial health and popular new products protect it from broader economic downturns.

  • Rapid sales growth of its leading skin-treatment drug is driving the company's overall financial success and market share gains.
  • An exceptionally low debt level completely protects the company from rising interest rates and global credit market stress.
  • High cash generation allows the business to easily fund its own research and future products without relying on banks.
  • Building new factories in the US protects the company's supply chain from global political tensions and trade disruptions.
  • Recent company purchases of smaller biotech firms may temporarily lower profits but will secure long-term growth and new products.
  • Government drug pricing rules in the US remain a key risk that could limit future profit margins on key treatments.

Advisor consensus

The primary disagreements across the reports center on the valuation multiple and near-term margin trajectories. Some perspectives argue that the current multiple of 29x P/E is fully justified by explosive top-line growth, while others caution that it leaves zero margin of safety, predicting a prolonged sideways valuation compression. Disagreements also stem from differing assumptions regarding the impact of recent acquisitions; some view the R&D spend as a prudent, self-funded capital allocation strategy to bridge a clinical catalyst desert, while others penalize it as structural margin decay.

Risk and opportunity map

Longer-term opportunities

Accelerated Broad Label Expansion

Innovation And Product

40% probabilityStock price impact: +20.0%Earnings impact: Not quantified

Regulatory agencies could grant earlier-than-expected approvals for the flagship immunology drug across a wider spectrum of autoimmune indications. This would dramatically expand the total addressable market, resetting peak sales estimates upward by billions of dollars and forcing a structural upward re-rating of the equity multiple.

Predatory Distressed Biotech Acquisitions

Capital Allocation

30% probabilityStock price impact: +15.0%Earnings impact: Not quantified

Leveraging its fortress balance sheet and massive free cash flow, the company could execute highly accretive, counter-cyclical acquisitions of distressed clinical-stage biotech firms. In a high-rate environment where smaller peers face capital starvation, acquiring late-stage assets at firesale valuations would rapidly replenish the long-term pipeline without diluting equity.

Tail risks

Post-Marketing Safety Signal Emergence

Innovation And Product

15% probabilityStock price impact: -35.0%Earnings impact: Not quantified

Real-world commercial data could reveal an unexpected, severe post-marketing safety signal associated with a core growth driver. This would lead to immediate regulatory black-box warnings or restricted prescribing protocols, collapsing the drug's commercial trajectory, destroying the primary growth thesis, and triggering a severe valuation downgrade.

Drastic US Price Controls

Regulatory

25% probabilityStock price impact: -25.0%Earnings impact: Not quantified

Populist political momentum in the US could result in the implementation of hard international reference pricing or sweeping price controls on biologics. Because the US market drives the vast majority of the company's profitability, this structural shift would permanently compress gross margins and severely restrict pipeline reinvestment capacity.

ENGI:PARHQ:Listed:

Utilities · Electric Utilities

French multinational electric utility company focusing on renewable energy, natural gas, and energy services. important player in the global energy transition.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Massive power demand from new AI data centers allows the company to lock in highly profitable, long-term contracts.

What to watch

An European sovereign debt crisis could freeze funding markets and pressure dividends, capital spending, and balance-sheet flexibility.

+146.0%
Excl. dividends: +79.9%
6.4%Dividend yield (net)
0.0%Buyback yield
9.6x
26/100
74/100

Flagship insight

How Sovereign AI Power Demands Are Quietly Repricing Legacy Grid Infrastructure

There is high consensus across reports that structural energy scarcity and exponential AI datacenter power demands are transforming legacy grid infrastructure into premium strategic assets. While elevated interest rates and heavy capital expenditure present near-term balance sheet friction, long-term power purchase agreements provide a robust, inflation-protected cash flow floor.

The company is undergoing a major transformation from a traditional power company into a vital backbone for Europe's energy independence and the AI revolution. While heavy spending on new green energy projects and high interest rates are currently squeezing cash flows, this massive investment is building a strong competitive advantage. By shifting away from risky energy trading and nuclear liabilities toward regulated power grids and long-term contracts with major technology firms, the business is securing safer, more predictable profits that will support its attractive dividend payments over time.

  • Heavy spending on green energy and power grids is creating a massive, hard-to-replicate competitive advantage.
  • Getting rid of long-term nuclear cleanup liabilities removes a major financial risk that previously worried investors.
  • Massive power demand from new AI data centers allows the company to lock in highly profitable, long-term contracts.
  • High interest rates and heavy debt loads will continue to pressure short-term cash flows and limit quick growth.
  • Governments may step in with price caps or extra taxes if energy prices spike, capping short-term profit upside.
  • The company's high dividend yield provides immediate, reliable returns to shareholders while waiting for long-term investments to pay off.

Advisor consensus

The primary disagreement across reports centers on the near-term trajectory of free cash flow and the timing of the valuation re-rating. Some models assume a rapid, mechanical cash flow rebound as derivative hedging collateral is returned and the Belgian nuclear exit is finalized. Other analyses apply a more conservative risk-weighting, emphasizing the immediate dilutive impact of the planned equity raise and potential execution delays in the massive renewable pipeline. Additionally, there is divergence regarding whether the company's margin expansion is a temporary, cycle-dependent anomaly or a permanent structural shift driven by tech-sector power purchase agreements.

Risk and opportunity map

Longer-term opportunities

Hyperscaler Sovereign Co-Location Pact

Competitive Positioning

38% probabilityStock price impact: +22.0%Earnings impact: Not quantified

The company could secure exclusive, sovereign-approved co-location partnerships with major technology hyperscalers, building data centers directly inside its massive renewable and battery storage parks. This would bypass paralyzed national grid connection queues entirely, delivering turnkey green power. This below-50% probability event would instantly re-rate the stock from a regulated utility to a high-multiple AI infrastructure monopoly, locking in premium, long-term contracted cash flows.

EU Strategic Grid Subsidization

Political And Geopolitical

28% probabilityStock price impact: +13.0%Earnings impact: Not quantified

In response to severe energy security concerns, the European Union could launch a massive, non-dilutive strategic grant program to fully fund grid and transmission modernization. This unexpected capital injection would dramatically lower the company's capital expenditure burden while allowing it to earn regulated returns on the expanded infrastructure, instantly expanding free cash flow yields and boosting the intrinsic value of the enterprise.

Tail risks

European Sovereign Debt Crisis

Macroeconomic And Macrofinancial

26% probabilityStock price impact: -25.0%Earnings impact: Not quantified

A severe escalation in European stagflation or political instability could trigger a sovereign debt crisis, causing credit spreads to blowout and freezing wholesale funding markets. For a highly leveraged utility reliant on debt markets to roll over billions in infrastructure paper, this liquidity freeze would force a brutal dividend cut, capex cancellations, and highly dilutive emergency equity issuances to preserve solvency.

Belgian Nuclear Deal Collapse

Political And Geopolitical

22% probabilityStock price impact: -20.0%Earnings impact: Not quantified

If political gridlock, state-aid disputes, or valuation disagreements cause the pending nuclear liability transfer negotiations to fail, the terminal decommissioning liabilities would violently boomerang back onto the balance sheet. The company would be forced to absorb billions in unexpected decommissioning cost overruns, destroying the de-risking thesis and triggering a massive sell-off as the legacy utility discount is re-applied.

The leading five

The Top 5

#5 → #1

Five ideas remain. Each passed the full editorial review and earned a place in this edition's highest-conviction group.

1024:HKEXHQ:Listed:

Communication Services · Interactive Media & Services

Kuaishou Technology, an investment holding company, provides live streaming, online marketing, and other services in the People's Republic of China.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Management is actively buying back stock and paying dividends, which helps protect the share price from falling further.

What to watch

An AI spin off funding collapse could shift heavy funding needs back to the parent and weaken free cash flow.

+165.0%
Excl. dividends: +157.0%
0.7%Dividend yield (net)
0.0%Buyback yield
8.3x
54/100
46/100

Flagship insight

How Off-Balance-Sheet Restructuring Is Unlocking Hidden Value In Short-Video Platforms

There is high consensus that the strategic spin-off of a frontier artificial intelligence unit will structurally re-rate the parent platform. By externalizing massive computing expenditures, the core short-video business emerges as an unencumbered cash generator, offsetting severe domestic macroeconomic headwinds and intense competitive duopoly pressures.

The main story is that this company is undergoing a major corporate split that will reveal its true value. Right now, investors are worried about the heavy spending required to build advanced artificial intelligence tools. However, by spinning off its artificial intelligence division and securing outside funding, the company is protecting its highly profitable core business of short-form video and online shopping.

  • Splitting off the artificial intelligence unit removes a massive spending burden from the main company's books.
  • The core video app remains highly popular, serving as a cheap source of entertainment during economic downturns.
  • Management is actively buying back stock and paying dividends, which helps protect the share price from falling further.
  • Weak consumer spending in the home market and fierce competition from larger rivals remain the biggest ongoing challenges.
  • A future public listing of the artificial intelligence business will help investors see the true value of both parts.
  • New smart software tools are helping merchants sell more goods on the platform, boosting advertising revenues.

Advisor consensus

The primary disagreement across the reports centers on the timing and execution risk of the corporate restructuring. While there is high consensus that the spin-off of the artificial intelligence unit is the correct strategic path, some reports assume a rapid, seamless deconsolidation of capital expenditures by late 2026, while others adopt a more cautious horizon, highlighting potential regulatory delays or funding bottlenecks. Additionally, analysts disagree on the long-term growth potential of the core e-commerce business, with some projecting steady-state utility margins and others forecasting incremental gains from agentic AI integration.

Risk and opportunity map

Longer-term opportunities

Kling AI Standalone Blockbuster IPO

Capital Allocation

42% probabilityStock price impact: +35.0%Earnings impact: Not quantified

A successful standalone public listing of the Kling AI unit in Hong Kong or the STAR market at a valuation exceeding twenty-five billion dollars. This discrete event would establish a liquid market price for the artificial intelligence asset, forcing institutional models to mark the parent company's sixty-eight percent retained stake to market and triggering a rapid sum-of-the-parts re-rating.

Aggressive Direct Consumer Fiscal Stimulus

Macroeconomic And Macrofinancial

28% probabilityStock price impact: +25.0%Earnings impact: Not quantified

The central bank and government pivot to a massive, direct-to-consumer fiscal stimulus package targeting lower-income demographics. This unexpected policy shift would rapidly unfreeze consumer confidence, directly re-igniting e-commerce transaction volumes and merchant advertising budgets. The high operating leverage of the digital platform would translate this demand shock into explosive net income expansion.

Tail risks

AI Spin-Off Funding Collapse

Capital Allocation

32% probabilityStock price impact: -38.0%Earnings impact: Not quantified

The external funding for the artificial intelligence unit is rapidly exhausted by escalating compute costs, and subsequent funding rounds fail due to market skepticism. The parent company would be forced to re-absorb the massive capital expenditure burden internally to keep the unit competitive, destroying core free cash flow, halting share buybacks, and invalidating the capital-light investment thesis.

Draconian Algorithmic Regulatory Crackdown

Regulatory

18% probabilityStock price impact: -45.0%Earnings impact: Not quantified

Regulators impose severe restrictions on short-video recommendation engines, daily screen time, or live-streaming monetization models to curb digital addiction. This sudden policy intervention would disrupt the platform's core engagement loops, leading to rapid user churn and a structural decline in advertising and tipping revenues, permanently impairing the company's cash-printing capabilities.

2333:HKEXHQ:Listed:

Consumer Discretionary · Automobile Manufacturers

Great Wall Motor Company Limited engages in the manufacture and sale of automobiles, and automotive parts and components in the People's Republic of China, Europe, ASEAN countries, Latin America.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Strong sales of popular off-road SUVs and trucks help protect profits from cheap electric car competition.

What to watch

A Secondary sanctions on overseas assets could force overseas closures, reducing profits and creating material asset write-downs.

+169.0%
Excl. dividends: +129.0%
3.3%Dividend yield (net)
0.0%Buyback yield
9.9x
44/100
59/100

Flagship insight

Why This Overlooked Global South Automotive Giant Is Set to Reprice

High consensus across reports reveals a structurally undervalued automotive manufacturer successfully bypassing Western tariffs through Global South localization. While domestic price wars compress near-term margins, the primary driver remains immense free cash flow generation, while geopolitical sanctions and shipping bottlenecks represent the chief risks.

This company is undergoing a major shift from a local Chinese carmaker to a global automotive powerhouse. While the media focuses on the intense price wars in China and new Western tariffs, the company is quietly building factories in regions like Latin America, Southeast Asia, and Russia to bypass these barriers. Backed by a debt-free balance sheet and massive cash generation, the business is highly resilient and well-positioned to survive domestic competition while growing its profitable export business. This strategy protects the company from global economic shocks.

  • Strong sales of popular off-road SUVs and trucks help protect profits from cheap electric car competition.
  • Building local factories in friendly countries allows the company to avoid heavy US and European tariffs.
  • The company generates huge amounts of cash, allowing it to fund its own global expansion without borrowing.
  • A major risk is that Western countries could pressure emerging markets to block Chinese vehicle sales.
  • Offering hybrid and traditional engines fits perfectly with developing nations that lack electric charging stations.
  • Plans to buy back up to ten percent of its own shares should support the stock price.

Advisor consensus

The primary disagreement across the reports centers on the long-term outlook for hardware manufacturing versus software integration. Some perspectives argue that the company is structurally obsolete, viewing it as a low-margin hardware provider vulnerable to autonomous driving software monopolies. Conversely, other reports emphasize the company's role as an all-weather compounder, arguing that its massive free cash flow and pragmatic hybrid strategy provide a durable moat. There is also divergence regarding the persistence of domestic margin compression and the speed at which localized overseas plants can achieve profitability.

Risk and opportunity map

Longer-term opportunities

Accelerated Domestic Industry Consolidation

Sector And Industry

35% probabilityStock price impact: +25.0%Earnings impact: Not quantified

If the brutal domestic price war triggers widespread bankruptcies among weaker Chinese automakers, significant market share will be liberated. The company's fortress balance sheet and massive cash reserves position it to survive this attrition, allowing it to absorb orphaned market share and rapidly restore domestic pricing power.

Global Luxury Brand Breakout

Competitive Positioning

30% probabilityStock price impact: +20.0%Earnings impact: Not quantified

If global consumer adoption of the company's premium off-road SUV brand accelerates beyond emerging markets into premium segments in Australia and the Middle East, it would fundamentally alter the corporate margin profile. This shift from volume-driven to margin-driven sales would force a substantial upward re-rating of the stock's valuation multiple.

Tail risks

Secondary Sanctions on Overseas Assets

Political And Geopolitical

20% probabilityStock price impact: -35.0%Earnings impact: Not quantified

If Western powers weaponize secondary sanctions against Chinese manufacturers operating physical assets in non-aligned nations like Russia, the company could be forced to shutter highly profitable localized plants. This would instantly sever its most accretive export profit engine and require massive asset write-downs.

Emerging Market Tariff Contagion

Regulatory

25% probabilityStock price impact: -30.0%Earnings impact: Not quantified

If key emerging markets in Latin America or Southeast Asia implement high tariffs to protect their own domestic auto industries against Chinese imports, the company's primary growth engine would stall, trapping excess capacity inside China and leading to severe margin collapse.

The finalists

The Top 3

#3 → #1

The shortlist is over. These three stocks earned the strongest conviction in this edition. Count down to the research team's number-one pick.

POWERGRID:NSEHQ:Listed:

Utilities · Electric Utilities

Indian state-owned electric utilities company operating the nationwide power transmission network in India with nationwide coverage.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Government rules guarantee a steady profit on new power lines, making future earnings highly predictable and secure.

What to watch

A Regulatory ROE reset could compress earnings and reduce the value of the existing asset base.

+150.0%
Excl. dividends: +89.1%
5.8%Dividend yield (net)
0.0%Buyback yield
12.6x
37/100
93/100

Flagship insight

Why Markets Misprice The Massive Capital Expansion Of Sovereign Grid Infrastructure

High consensus across reports indicates that massive capital expenditure is structurally compounding the regulated asset base, despite short-term negative free cash flow. While rising interest rates present a persistent macroeconomic friction, the sovereign-backed grid expansion remains the critical bottleneck for national electrification and artificial intelligence compute demands.

This company is the main power highway builder for a rapidly growing nation. While it is spending heavily right now to upgrade the power grid for renewable energy and new technology like artificial intelligence, this spending is actually a good thing. Under government rules, the company is guaranteed a steady profit on the infrastructure it builds. This means today's heavy spending will turn into highly predictable, guaranteed profits tomorrow, protecting the business from global economic ups and downs. For everyday investors, this offers a rare combination of safety and steady growth.

  • Government rules guarantee a steady profit on new power lines, making future earnings highly predictable and secure.
  • The massive shift to clean energy and new technology like artificial intelligence requires a huge expansion of the power grid.
  • Strong government backing allows the company to borrow money cheaply, keeping its expansion costs low even when interest rates rise.
  • Increased competition from private companies could slightly lower profit margins on some new competitive projects.
  • Delays in getting land and building new power lines could slow down how fast new profits start rolling in.
  • The business is well-protected against inflation because it can pass rising interest and operating costs onto its customers.

Advisor consensus

The primary disagreement across the reports centers on the interpretation of the massive capital expenditure spike and the resulting negative free cash flow. Some perspectives view this capital intensity as a highly bullish, guaranteed-return compounding mechanism that secures long-term earnings power. Conversely, more cautious assessments emphasize the near-term return dilution, rising debt servicing costs, and the risk of diminishing marginal returns under the slightly lower return on equity allowed for new assets. There is also minor disagreement regarding the severity of competitive bidding pressures and the potential for execution delays to defer tariff recognition.

Risk and opportunity map

Longer-term opportunities

Transnational Grid Integration

Political And Geopolitical

25% probabilityStock price impact: +20.0%Earnings impact: Not quantified

The successful execution of cross-border grid interconnections linking the domestic grid with neighboring regions or the Middle East. This would transform the company into a transnational energy exchange hub, opening massive new geopolitical revenue streams and expanding the total addressable market beyond domestic boundaries.

Grid-Scale Battery Storage Dominance

Innovation And Product

35% probabilityStock price impact: +15.0%Earnings impact: Not quantified

The designation of the company as the central nodal agency for grid-scale Battery Energy Storage Systems. Integrating chemical storage directly into the transmission asset base would allow the company to capture high-margin ancillary services, breaking the standard regulated-return ceiling and doubling its addressable market.

Tail risks

Punitive Regulatory ROE Reset

Regulatory

20% probabilityStock price impact: -25.0%Earnings impact: Not quantified

A sudden, politically motivated reduction in the guaranteed return on equity by the regulatory commission to alleviate tariff pressures on consumers. A significant cut to the allowed return would instantly compress the company's earnings power and permanently impair the valuation of the existing asset base.

Catastrophic Grid Cyber-Attack

Operational Efficiency

12% probabilityStock price impact: -20.0%Earnings impact: Not quantified

A targeted, state-sponsored cyber-intrusion that physically compromises critical transmission infrastructure or causes a cascading multi-state blackout. This would destroy the operational infallibility narrative, forcing massive uncompensated defensive capital expenditure and severe regulatory penalties.

HDFCBANK:NSEHQ:Listed:

Financials · Regional Banks

Large Indian private sector bank providing banking and financial services including retail, wholesale, and treasury operations.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

A massive network of branches allows the bank to gather cheap deposits, giving it a huge advantage over competitors.

What to watch

A Stagflation induced retail credit bust could increase defaults and provisions, weakening profitability and valuation.

+132.0%
Excl. dividends: +120.0%
1.0%Dividend yield (net)
0.0%Buyback yield
13.9x
52/100
78/100

Flagship insight

Why the Market Misprices This Sovereign Financial Giant Post Merger Integration

High consensus across reports indicates that temporary post-merger integration friction has created a generational valuation mismatch. While global liquidity tightening acts as a persistent headwind, the primary driver remains the bank's unassailable low-cost deposit franchise, while the main risk centers on potential retail credit quality degradation.

The company is currently recovering from a massive merger that temporarily lowered its profitability and squeezed its profit margins. Many investors are worried about these short-term issues, but the bank's core business of collecting deposits and lending money remains incredibly strong. As the merger issues are resolved and expensive older debts are paid off, the bank's profits are expected to bounce back strongly, supported by India's fast-growing economy.

  • A massive network of branches allows the bank to gather cheap deposits, giving it a huge advantage over competitors.
  • The bank can now sell credit cards, personal loans, and insurance to millions of new home-loan customers gained from the merger.
  • Recent changes in leadership and independent reviews have cleared up previous worries about corporate governance and management.
  • Intense competition for deposits across the banking sector remains a key challenge that could keep funding costs high.
  • The planned stock market debut of its financial services subsidiary will help unlock hidden value for shareholders.
  • High global energy prices and inflation could pressure everyday borrowers, though the bank's loan quality remains excellent.

Advisor consensus

The primary disagreement across the reports centers on the timeline and trajectory of net interest margin recovery and loan-to-deposit ratio normalization. Some assessments assume a rapid, mechanical improvement within the next twelve months as high-cost legacy borrowings mature and are replaced by cheap deposits. Conversely, other reports adopt a more conservative horizon, arguing that intense systemic competition for retail deposits and persistent central bank hawkishness will prolong the margin drag. Additionally, there is minor disagreement regarding the potential impact of digital public infrastructure on fee-income margins.

Risk and opportunity map

Longer-term opportunities

Subsidiary Value Unlocking via IPO

Capital Allocation

45% probabilityStock price impact: +15.0%Earnings impact: Not quantified

The highly anticipated public listing of the bank's rapidly growing non-banking financial subsidiary would immediately crystallize significant sum-of-the-parts value. This strategic divestment would inject fresh core capital into the parent balance sheet, boosting capital adequacy ratios and forcing a major upward re-rating of the consolidated entity by institutional investors.

Accelerated Central Bank Easing Cycle

Macroeconomic And Macrofinancial

35% probabilityStock price impact: +18.0%Earnings impact: Not quantified

Should domestic inflation cool faster than anticipated, the central bank could initiate a rapid rate-cut cycle. This monetary easing would immediately lower the bank's wholesale borrowing costs and term deposit rates, triggering an asymmetric expansion in net interest margins and substantial mark-to-market treasury gains on its massive government securities portfolio.

Tail risks

Stagflation-Induced Retail Credit Bust

Macroeconomic And Macrofinancial

25% probabilityStock price impact: -25.0%Earnings impact: Not quantified

A prolonged global energy crisis could plunge the domestic economy into a stagflationary recession. As inflation erodes household savings, the bank's rapidly expanding unsecured retail loan book could experience unprecedented defaults. A sharp rise in non-performing assets would force heavy provisioning charges, severely impairing profitability and eroding the bank's premium valuation.

Draconian Regulatory Tightening

Regulatory

20% probabilityStock price impact: -20.0%Earnings impact: Not quantified

The central bank could impose hard regulatory caps on incremental loan-to-deposit ratios or aggressively hike liquidity coverage requirements to cool systemic credit growth. Such intervention would virtually paralyze the bank's ability to originate high-margin retail loans, stalling top-line revenue growth and permanently lowering its return on equity.

The winner

The Number-One Pick

The edition's highest-conviction selection, combining near-term opportunity with long-term confirmation.

CLBT:NASDAQHQ:Listed:

Information Technology · Application Software

Digital intelligence company providing investigative analytics, device extraction, and evidence management tools for public and private sectors.

RatingStrong Buy

Latest editorial review

Reviewed through 7 Sept 2026

Based on deep-analysis report: 5 Jul 2026 · newer evidence is included through the review date

Thesis remains current

Review conclusion

The latest editorial review continues to support the original investment case and current rating.

What the editor likes

Strong customer loyalty is driven by the high difficulty of changing courtroom-approved forensic tools.

What to watch

A Hardware encryption lockdown could block device extraction and weaken the data foundation for renewals and analytics.

+180.0%
Model rating: Buy
0.0%Dividend yield (net)
0.0%Buyback yield
49.3x
69/100
55/100

Flagship insight

Why Sovereign Security Budgets Are Creating An Unassailable Digital Intelligence Monopoly

There is high consensus that this digital intelligence asset commands an unassailable judicial moat. While restrictive monetary policy pressures valuation multiples, expanding sovereign security budgets and agentic artificial intelligence integration drive structural cash-flow compounding, insulating the firm from broader macroeconomic demand destruction.

This company is a vital player in global public safety, helping police and governments unlock and analyze digital evidence. Because its tools are trusted by courts worldwide, customers rarely switch to competitors, creating a highly stable business. Even during tough economic times, governments continue to fund security and crime-fighting, making this business highly resilient to recessions and inflation.

  • Strong customer loyalty is driven by the high difficulty of changing courtroom-approved forensic tools.
  • Excellent cash generation allows the company to fund its own growth without taking on expensive debt.
  • The shift to subscription-based software ensures steady, predictable sales year after year.
  • Growing global security concerns keep government budgets focused on digital investigation tools.
  • A debt-free balance sheet protects the company from rising interest rates and economic downturns.
  • The main challenge is the constant need to update software to bypass new smartphone security features.

Advisor consensus

The primary disagreements across the reports center on the severity of geopolitical domicile risks and the competitive threat from private-equity-backed rivals. Some perspectives apply a heavy risk premium due to the Middle East conflict and potential personnel disruptions, while others view these concerns as temporary noise overshadowed by the firm's expanding federal monopoly. Additionally, there is minor divergence regarding the speed of the transition to agentic artificial intelligence, with differing assumptions on how quickly municipal police budgets can absorb premium software upgrades compared to well-funded federal agencies.

Risk and opportunity map

Longer-term opportunities

Enterprise Private Sector Breakthrough

Competitive Positioning

35% probabilityStock price impact: +30.0%Earnings impact: Not quantified

Successfully parlaying the core public safety technology into the corporate enterprise market for e-discovery and internal compliance investigations would double the total addressable market. This transition would unlock shorter sales cycles and larger corporate budgets that are less constrained by political cycles. Establishing the platform as the gold standard for corporate insider threat management would drive a colossal surge in high-margin recurring revenue.

Sovereign Defense Prime Acquisition

Capital Allocation

25% probabilityStock price impact: +35.0%Earnings impact: Not quantified

An outright acquisition by a major defense prime or a sovereign-aligned private equity firm would eliminate the geopolitical discount and parent company float overhang. This transaction would command a significant control premium to secure vital national security software. Moving the intellectual property under a domestic corporate umbrella would secure the ultimate political moat and accelerate adoption across allied intelligence networks.

Tail risks

Permanent Hardware Encryption Lockdown

Innovation And Product

20% probabilityStock price impact: -45.0%Earnings impact: Not quantified

A major smartphone manufacturer successfully deploys a closed-loop, hardware-isolated cryptographic architecture that permanently defeats physical extraction. This would destroy the core data-ingestion utility, causing massive customer churn and a collapse of the software narrative. Without raw data feedstock, downstream artificial intelligence and cloud analytics products would starve, leading to contract non-renewals and a structural decline in forward recurring revenues.

Catastrophic Source Code Breach

Operational Efficiency

10% probabilityStock price impact: -50.0%Earnings impact: Not quantified

A state-sponsored cyber breach leaking proprietary extraction methodologies and zero-day exploits would allow manufacturers to immediately patch vulnerabilities. This would destroy courtroom trust, invalidate past evidence chains, and trigger immediate contract cancellations. Reputational ruin from a breach of this magnitude would lead to severe capitulation as environmental, social, and governance mandates force institutional liquidations globally.

Market context and selection approach

Markets remain selective, so this review emphasizes local demand, currency and policy exposure, financial strength, and execution. Current evidence can support a thesis while still leaving meaningful company, policy, liquidity, or macro risk.

The list favors the strongest eligible assets and excludes any name whose current evidence no longer supports its investment case. It never adds a weaker asset simply to make the list longer.

References

Frozen links are separated into editorial-review evidence, 5–6 global-context references, and 3–4 governed Researcher citations per selected asset. Duplicate URLs appear once; the combined citation list is capped at 30.

A. Editorial-review sources

  1. 1.Cellebrite Appoints Shiven Ramji Chief Executive Officer Cellebrite DI Ltd · ISSUER RELEASE · 13 Aug 2026, 00:00 UTChttps://investors.cellebrite.com/news-releases/news-release-details/cellebrite-appoints-shiven-ramji-chief-executive-officerReviewed for: Cellebrite DI Ltd (CLBT.NASDAQ)
  2. 2.HDFC Bank Announces Financial Results for the Quarter Ended June 30, 2026 HDFC Bank Limited · ISSUER FILING · 18 Jul 2026, 00:00 UTChttps://www.sec.gov/Archives/edgar/data/1144967/000119312526308398/d101962dex99.htmReviewed for: HDFC Bank Limited (HDFCBANK.NSE)
  3. 3.Integrated Financial Filing for the Quarter Ended June 30, 2026 National Stock Exchange of India · EXCHANGE NOTICE · 5 Aug 2026, 00:00 UTChttps://nsearchives.nseindia.com/corporate/ixbrl/INTEGRATED_FILING_INDAS_182975_05082026230017_iXBRL_WEB.htmlReviewed for: Power Grid Corporation of India Limited (POWERGRID.NSE)
  4. 4.Great Wall Motor Releases July 2026 Sales Results Great Wall Motor Co Ltd · ISSUER RELEASE · 6 Aug 2026, 00:00 UTChttps://www.gwm-global.com/news/3403979.htmlReviewed for: Great Wall Motor Co Ltd (2333.HKEX)
  5. 5.Kuaishou Technology Announces Second Quarter and Interim 2026 Results Kuaishou Technology · ISSUER RELEASE · 19 Aug 2026, 00:00 UTChttps://ir.kuaishou.com/news-releases/news-release-details/kuaishou-technology-announces-second-quarter-and-interim-2026Reviewed for: Kuaishou Technology (1024.HKEX)
  6. 6.ENGIE 2026 First-Half Financial Results ENGIE SA · ISSUER RELEASE · 31 Jul 2026, 00:00 UTChttps://www.engie.com/en/investors/financial-publications/Reviewed for: Engie SA (ENGI.PAR)
  7. 7.UCB Delivers Strong Results, Raises 2026 Guidance and Positions for Next Growth Phase UCB SA · ISSUER RELEASE · 30 Jul 2026, 00:00 UTChttps://www.ucb.com/newsroom/press-releases/article/ucb-delivers-strong-results-raises-2026-guidance-and-positions-for-next-growth-phaseReviewed for: UCB SA (UCB.BRU)
  8. 8.Novo Nordisk Financial Results for the First Half of 2026 Novo Nordisk A/S · ISSUER RELEASE · 4 Aug 2026, 00:00 UTChttps://www.novonordisk.com/news-and-media/news-and-ir-materials/news-details.html?id=916589Reviewed for: Novo Nordisk A/S (NOV.XETRA)
  9. 9.NetEase Announces Second Quarter and Interim 2026 Unaudited Financial Results NetEase, Inc. · ISSUER RELEASE · 20 Aug 2026, 00:00 UTChttps://ir.netease.com/news-releases/news-release-details/netease-announces-second-quarter-and-interim-2026-unauditedReviewed for: NetEaseInc (9999.HKEX)
  10. 10.XPENG Reports Second Quarter 2026 Unaudited Financial Results XPeng Inc. · ISSUER RELEASE · 24 Aug 2026, 00:00 UTChttps://ir.xiaopeng.com/zh-hans/news-releases/news-release-details/xpeng-reports-second-quarter-2026-unaudited-financial-resultsReviewed for: Xpeng Inc (9868.HKEX)

B. Global market context

These dated files capture broader market, macroeconomic, policy, and cross-asset context. Each frozen file is supplied as input to every advisor model during deep analysis; its citations never count toward an asset-specific minimum.

This legacy draft has no governed global-context references. Rematerialization is required before approval.

C. Asset-specific deep-analysis sources

Captured by governed AI Researcher agents. Shared URLs are shown once and identify every selected asset they support.

This legacy draft has no governed asset-specific URLs. Fresh Researcher evidence and rematerialization are required before approval.

Important information

Research scope and investor notice

Research scope

  • The post-cutoff source state is NOT_RETAINED where no newer primary-source document was available; retained official sources were reused without inventing citations.
  • This editorial review does not rerun forecasts or guarantee that every fast-moving company, policy, protocol, market, or geopolitical development has been captured.

Investor notice

AI-assisted editorial analysis. Reviewed and approved by Russlan Ramdowar. Published by Future Edge Group FZE. This is general research, not personalized investment advice.

Forecasts, ratings, and return estimates are uncertain and may change as new evidence becomes available.