Fresh research, big ideas and conversations from iPulse AI.
AI Investment Edge · from iPulse AI
Tesla: Roadster Thrills. Can the Cash Follow?
Tesla’s flying Roadster puts extraordinary engineering on display. The investment test is whether cars, storage and AI can generate enough cash to justify the price and fund the buildout. Tesla sells electric vehicles, Megapack and Powerwall storage, charging, services and softwa
 Explore Tesla Investment Thesis
In This Episode
Tesla: Roadster Thrills. Can the Cash Follow? | EP 022
Tesla’s flying Roadster puts extraordinary engineering on display. The investment test is whether cars, storage and AI can generate enough cash to justify the price and fund the buildout.
Tesla sells electric vehicles, Megapack and Powerwall storage, charging, services and software. Explore the Tesla analysis and forecast history and iPulse AI methodology.
The Roadster reveal
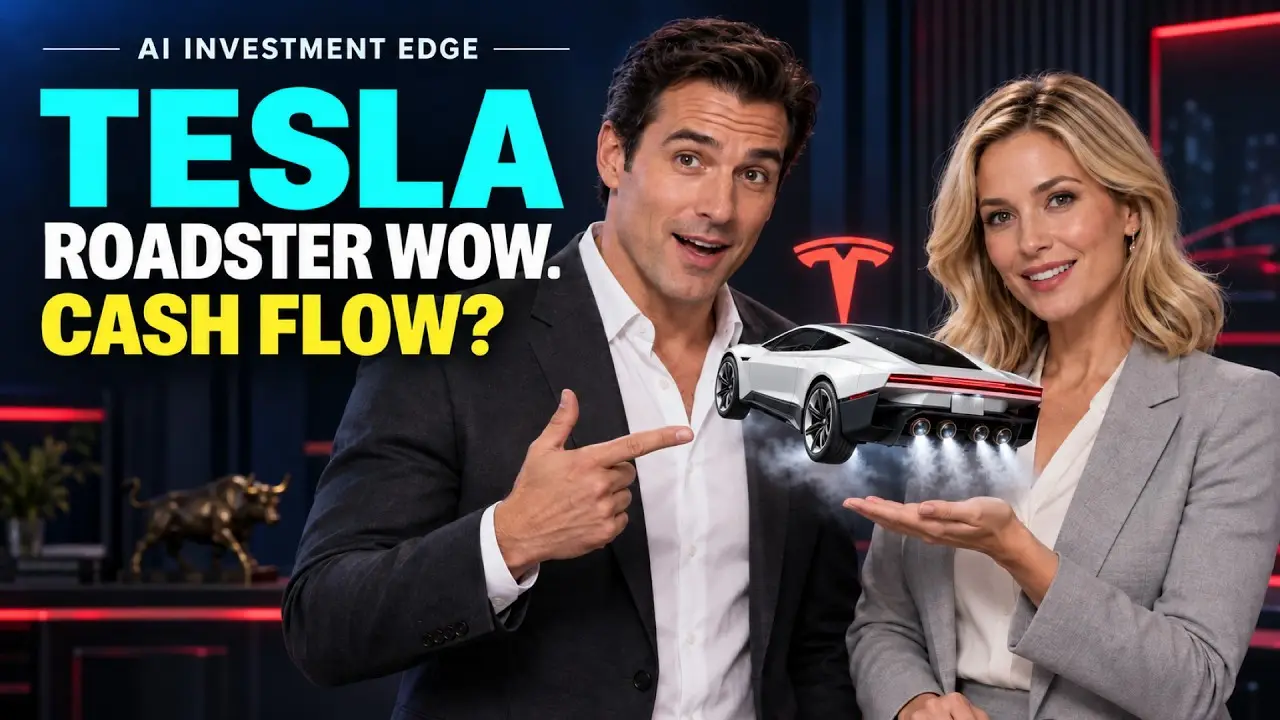
Tesla’s official event began at 04:55 Dubai on 16 October, the evening of 15 October in Texas. Its replay includes ramp, kickflip and acceleration demonstrations. The new angular silver-white Roadster combines active aero, suction and optional cold-gas thrusters. Tesla describes Performance and Thrust as two-seat versions; the invite-only Rocket seats one and is not approved for public-road use. The presenters reported 0.81 seconds for an acceleration run and a 2028 production target. These are Tesla’s demonstration report and target. The cover is an editorial illustration of the new airborne Roadster with fictional presenters.
Price and cumulative scenarios
TSLA.NASDAQ common shares, USD 368.13: an Alpaca IEX trade timestamped 16 October 2026 at 10:15:20 New York/18:15:20 Dubai. The same price is used for every percentage below. Endpoints remain 18 September 2027 and 18 September 2031.
Base: −15.9% to September 2027; −4.9% to September 2031.
Bull: −2.1% to September 2027; +57.7% to September 2031.
Bear: −32.7% to September 2027; −58.3% to September 2031.
The main conversation uses the public averaged scenario table consistently: base targets 309.71/349.92, bull 360.51/580.39, bear 247.60/153.34 USD. Tesla pays no cash dividend; annual and modeled future cash dividends are zero, so no dividend uplift is added. These are cumulative price scenarios to the stated dates.
Four financial findings
Earnings. Q2 revenue rose 26% to USD 28.236 bn, but operating income fell 57% to USD 398 m. After-tax GAAP common-stockholder net income was USD 1.114 bn. A separate pretax USD 1.005 bn unrealized SpaceX investment gain sits below the operating line. Taxes and other non-operating items bridge operating income to after-tax net income; the pretax mark cannot be equated with virtually all after-tax earnings. The noncash mark boosted earnings without adding operating cash.
Margins. Q2 operating margin was 1.4%, versus 4.1% a year earlier; gross margin was 16.8%. Revenue growth and profitable growth are separate tests.
Balance sheet. June cash, equivalents and short-term investments totalled USD 43.524 bn; debt and finance leases totalled USD 9.342 bn. Liquidity funds the transition while investment and operating obligations compete for cash.
Investment. Q2 operating cash USD 4.697 bn less capex USD 5.789 bn left negative USD 1.092 bn free cash flow. First-half cash flow USD 8.634 bn less capex USD 8.282 bn left positive USD 352 m. Current 2026 total-company capex guidance exceeds USD 25 bn, spanning AI compute, data centres, manufacturing and other assets. Periods and cash flow measures are not interchangeable.
These financials cover the quarter ended 30 June, released 22 July. Q3 operations announced 2 October were 486,532 deliveries, 464,391 vehicles produced and 13.7 GWh storage deployed. Q3 financial results are scheduled 21 October after the US close; Q&A 17:30 New York/01:30 Dubai on 22 October.
What would change the thesis?
Watch automotive margin recovery, storage profit and utilisation, recurring software cash, robotaxi operating costs, and cash generation relative to the capital programme. The bull needs commercial economics to follow engineering; the bear centres on margin pressure, investment absorption and valuation compression. Supply disruption and autonomy liability are concrete tail risks; broader authorised deployment and useful robotics are upside mechanisms.
Complete averaged scenario path
All percentage changes below are from USD 368.13, excluding dividends.
| Quarter | Bear cumulative price return | Base cumulative price return | Bull cumulative price return |
|---|---|---|---|
| -18.9% | -7.8% | -5.0% | |
| -31.0% | -13.4% | -4.6% | |
| -27.9% | -14.7% | -6.2% | |
| -32.7% | -15.9% | -2.1% | |
| -36.1% | -16.3% | +1.8% | |
| -40.6% | -18.3% | -1.6% | |
| -38.8% | -16.0% | +3.2% | |
| -42.5% | -15.8% | +8.4% | |
| -39.6% | -15.4% | +11.6% | |
| -43.8% | -15.6% | +12.9% | |
| -46.7% | -12.8% | +19.7% | |
| -49.9% | -13.3% | +23.3% | |
| -48.9% | -12.2% | +28.2% | |
| -51.4% | -11.5% | +32.1% | |
| -53.4% | -10.2% | +37.3% | |
| -55.7% | -10.0% | +40.1% | |
| -54.4% | -7.7% | +45.3% | |
| -56.2% | -8.0% | +50.1% | |
| -57.5% | -5.9% | +53.1% | |
| -58.3% | -4.9% | +57.7% |
Companion conversations
BMW: Can Neue Klasse Pay for Itself? | EP 017 — New vehicle platforms, reinvestment and payback. Listen · Watch.
BYD: EV King or Cash Trap? | EP 015 — EV competition, pricing and manufacturing investment. Listen · Watch.
NVIDIA: Where’s the Cash? | EP 013 — Supplying AI compute versus investing in and monetising it. Listen · Watch.
Stay tuned for SpaceX, next on AI Investment Edge: launch, connectivity and the economics behind the engineering. Listen, watch or subscribe to continue the research conversation.
Research details
The main scenario table uses published averaged cases. The separate evidence-weighted synthesis targets 310.9598/343.0170 USD at the same dates, equal to -15.5%/-6.8% from 368.13; its 20-quarter path is preserved with the production evidence. These are different aggregations. Compared with July, the research became more skeptical while panel composition expanded from 12 contributions/one model to 14/three. The October operating update and Roadster event are subsequent context, not causes of the earlier September research shift. The previous public stock episode was Volkswagen 18; Silver 20 was the latest episode overall.
The financial discussion combines the four published consensus reviews with the primary filings linked below. The price scenarios and underlying research remain inspectable on the Tesla page.
Primary sources
Current Roadster page · Official Roadster event · Q2 shareholder update · Q2 SEC filing · Q3 operations and earnings date · Annual filing and dividend policy.
AI Investment Edge from iPulse AI. Narration uses Google NotebookLM/Gemini Notebook’s two synthetic presenters. Visual presenters are fictional adults.
Full Transcript
Reviewed 16 Oct 2026 · Edited captions reviewed against the published production take. Display corrections may clarify names and figures; this is not a verbatim legal record. Select a timestamp to listen from that point. Download transcript
Full transcript · 30-second passages
You know, usually when we talk about an automotive engineering reveal, there's this very standard, almost tired playbook. Oh, absolutely. Yeah, like you run out a stage, you take the covers off some sleek new design, maybe an executive touts some horsepower numbers and, well, everyone claps. Right. It's very predictable. Exactly. But what we saw recently with the Tesla Roadster, it completely shattered that playbook. I mean, we are talking about making the flying car idea actually tangibly real. Yeah, it was an undeniable spectacle and an incredibly effective one at that, you know, purely from a physics and branding standpoint.
Right. I mean, for you listening, whether you caught the official event live on October 16th in Dubai or you were watching the evening of October 15th out in McGregor, Texas, it was just mind bending. Truly. You had Tesla and SpaceX engineers up there demonstrating a car doing actual kickflips. They were ramping it. They demonstrated an astonishing 0.81 second acceleration time.
It's just the kind of thing that commands global attention. It really does. And that brings us to why we are here. So welcome to this deep dive from AI Investment Edge from iPulse AI. Today, we are taking a hard look at the company behind that incredible spectacle. And that really establishes our mission for this deep dive because, well, while the Roadster is phenomenal at capturing the world's imagination, the overarching investment question for you, the listener, is fundamentally different. Yeah. It's basically this. Can the company make its cash rise as quickly as its cars?
Like, can they take all of this extraordinary technological prowess and actually turn it into recurring, durable earnings? Okay. So let's unpack this. Because as mind-blowing as a flying Roadster is, we have to transition from the hype to the actual reality of the business. Right. We have to look at the numbers. Yeah. The Roadster is the flashy billboard on the highway. But what is actually paying the electric bill here? When we look under the hood of the business, we're looking at the real revenue drivers.
So that's the Model 3, the Model Y, the Cybertruck, the massive megapacks for utility grids, Powerwall storage for homes, the charging networks, and, you know, the software. Exactly. And selling those products means dealing with car buyers, utility companies, everyday households. Those are entirely different customer bases. Very different. Yeah. And serving them requires immense scale, supply chain logistics, and just operational execution, which is a completely different game than building an isolated engineering showcase.
But just to put a bow on that showcase, because the details really are wild, let's just talk about the three new Roadster variants they laid out for the future. Oh, sure. So first you have the performance tier, which is your road-ready two-seater. Then there's the thrust variant. This is a track-ready two-seater that actually uses rear cold gas thrusters. Which is wild. It is. And then here's where it gets really interesting. The rocket variant. This is an invite-only single-seater with perimeter thrusters and actual flight capability.
Obviously, it is not approved for public road use. Obviously. But the presenters up there reported a 2028 production ambition for the Roadster line. Which is a bold management target. But 2028 is a long way off. To your point about what pays the electric bill today, the largest funding and cash return questions right now concern the high-volume cars, the energy storage, and of course the AI investments. Right. If we connect this to the bigger picture, we need to look closely at some grounded financial realities from their Q2 2026 data.
This really outlines the underlying engine of the company. Let's get into the financials then. Where do we start? Let's start with their earnings, specifically looking at a very interesting SpaceX mark. In Q2 2026, their total revenue was $28.236 billion. Okay. That is actually up 26% year-on-year, which sounds great on the surface. However, their operating income was just $398 million.
Wow. Okay. Yeah. That operating income is down 57%. But then you look further down the page, and after-tax common-stockholder net income was reported at $1.114 billion. Okay. Hold on. I have to push back on those numbers for a second because I was looking through the income statement before we started, and I noticed a pre-tax $1.005 billion unrealized gain on Tesla's SpaceX investment sitting right there below operating income.
Right. I see where you're going with this. So let me get this straight. If the after-tax net income is $1.1 billion and the SpaceX gain is essentially $1 billion, did they basically make zero cash from the actual business of selling cars and batteries? Like, is that virtually all the net income? I am really glad you brought that up because it is a very common trap when reading these statements, but I need to firmly clarify this. These are fundamentally different bases. Okay. How so? Well, you have a pre-tax gain on one hand and an after-tax net income figure on the other.
You absolutely cannot simply equate the two or just subtract the pre-tax paper gain from the after-tax net income to claim the core business made nothing. Taxes and other non-operating items really matter here. Okay, but translate that for me. If they own a chunk of SpaceX and SpaceX becomes more valuable on paper, Tesla gets to claim that gain. But it's paper money. It doesn't pay for factory equipment. That's entirely true. So are they using paper gains from Elon's other company to make this quarter look better than it actually was?
Well, again, it is not a clean one-to-one subtraction. The similar size gross gain and the net income figures are not an after-tax earnings decomposition. However, your underlying suspicion is pointing in the right direction. Okay. The supportive conclusion remains valid here. A substantial non-cash fair value mark absolutely did boost reported earnings for the quarter while adding zero actual operating cash to the business.
Got it. So the paper gain made the headline earnings look better, but it didn't put a single dollar into the bank account to build the next factory. So if the cash isn't coming from paper gains, what is happening to the actual profit on the products they are selling? That brings us to the margins. The operating margin dropped to 1.4% compared to 4.1% a year earlier. Gross margin came in at 16.8%. Yikes. That's a big drop. Is that just from the price cuts? It is very tempting to look at a shrinking margin and just blame the highly publicized vehicle price cuts.
But price cuts are just one pressure point. They are not the sole explanation for the entire margin decline. What else is dragging it down? Product mix, underlying manufacturing costs, general expenses, and the massive investment burden of running this operation all play a part in shaping that operating profitability. But the bright spot here is that energy storage is clearly stepping up as a second growth engine, even as the overall group remains highly capital intensive. I mean, when your operating margin is shrinking down to 1.4% in a capital intensive business,
you suddenly need a massive safety net. Do they have the liquidity to weather that squeeze? They do. The balance sheet shows solid liquidity. If you look at June, their cash equivalents and short-term investments totaled $43.524 billion. That's a lot of cash. It is. And that is measured against $9.342 billion in debt and finance leases. That strong liquidity is essentially their war chest. It buys them vital time.
They have many competing calls on that cash, but the cushion is undeniably there. A war chest is great to have, but how fast are they burning through it? That is the crucial tension right now. It's their investment intensity, comparing their capital expenditures against their actual cash generation. In Q2, their operating cash flow was $4.697 billion. Okay. But their cash capex, so the money spent on physical assets and infrastructure, was $5.789 billion. That means they ran a negative $1.092 billion in free cash flow for the quarter.
Wow. They burned over a billion dollars in a single quarter just to keep the machine growing. Yes, but context is everything, and you really have to zoom out. For the first half of the year as a whole, operating cash was $8.634 billion, minus capex of $8.282 billion. Oh, okay. So for the half year, that actually leads a positive $352 million in free cash flow. The periods differ wildly based on when payments hit, so you have to look at the longer trend.
So what does the rest of the year look like for spending if they are trying to build out AI and robotics while also stamping out millions of cars? This is a detail you cannot ignore. Tesla's latest 2026 guidance requires total company capex in excess of $25 billion. And I want to stress this heavily. That $25 billion spans AI compute, data centers, manufacturing lines, factory expansions, and other company assets. So it's not just AI.
Right. It is a total company budget. It is not a separately disclosed AI-only budget. AI is a massive part of their future program, but software and autonomous fleet operations have very real, very heavy infrastructure costs, too. So what does this all mean for the valuation? Because looking at all this incredible capital intensity and margins squeezing down to 1.4%, the stock is still priced for absolute perfection. I mean, their trailing four-quarter GAAP earnings per share is $1.08.
Yes. That implies roughly a 341x trailing multiple. For you listening, a multiple like that is like paying $341 today for a business that only earned you $1 last year. That means future earnings must grow astronomically to support where the valuation is currently sitting. It is an incredibly demanding multiple, especially since that indicative trailing figure includes the effect of that non-cash SpaceX investment gain we just talked about.
Right. This raises an important question. Can a new massive technological platform actually earn its cost back? We actually discussed a very similar dynamic in a companion conversation, BMW EP-017. Can Neue Klasse pay for itself? Tesla is effectively asking that same question, but they are stretching it across vehicles, utility storage, and artificial intelligence all at once. That BMW deep dive is a fantastic parallel for you to check out if you want to understand the sheer grueling cost of platform transitions in the automotive world.
But let's bring it back to Tesla's stock right now. The current price reference we are looking at for this analysis is $368.13 USD. Exactly. And that is based on an IEX trade from October 16 at 10:15:20 New York time, which is 18:15:20 in Dubai. Right. And taking that exact baseline of $368.13, we can look at the averaged cumulative price returns from the research panel. These are modeled scenarios rebased to that exact mark, looking at where the price might go by specific endpoint dates.
So, September 18, 2027, and then out to September 18, 2031. Let's walk through those scenarios. What is the middle-of-the-road expectation? The base case. In the base case, the modeled return is down roughly 15.9% by 2027, recovering slightly to negative 4.9% by 2031. Okay. So, still negative.
Yes. This scenario assumes that their energy storage and services continue to grow nicely, but shareholder returns are ultimately constrained by those tightening auto margins. The massive $25 billion investment needs we just detailed, and a natural inevitable adjustment downward of that lofty 341X multiple. Okay. What if everything goes flawlessly? Like the absolute best case bull scenario. The bull case still projects a slight dip of negative 2.1% by 2027.
But then it models a massive leap to positive 57.7% by 2031. Oh, wow. Okay. Yeah, but this happens only if they achieve proven, profitable robotaxi unit economics, generate highly recurring cash from software subscriptions, scale their energy business vastly, and find deep new manufacturing efficiencies. And what happens if the weight of all this capital expenditure just crushes them? The bear case. The bear case sees a severe drop to negative 32.7% by 2027, deepening all the way to negative 58.3% by 2031.
This is the scenario where they face intense, unyielding competition, persistently low operating margins, heavy and unrewarded investment burdens, and much slower monetization of their AI bets. That sounds brutal. It would be. That combination would heavily and rapidly compress the valuation multiple. What stands out to me there is that even in the 2027 bull endpoint, like the absolute best case modeled scenario where everything goes right, the return is still negative 2.1%.
Yes, exactly. That just goes to show how incredibly demanding the starting price of $368 really is. And to make matters tougher for investors, Tesla pays zero cash dividends. Correct. So your annual and future dividend cash are zero. You get absolutely no dividend uplift while you wait for these long-term AI bets to pay off. Precisely. You are entirely reliant on capital appreciation.
You are holding the stock purely on the belief that the share price will rise. To understand how that future growth actually happens, or doesn't happen, we need to map out the economic battlefield. We look at this through four key quadrants before we get to the core thesis of the research. So if you are bidding the house on AI and robotics, what exactly are the forces working for and against them right now? Let's start with the drivers. This is the economic wind at their back.
So booming utility storage demand for those mega packs, increasing paid software adoption from drivers, manufacturing efficiency gains, and higher utilization of their global charging network. Okay. If these fire on all cylinders, revenue and cash generation improve significantly. But then you have the headwinds. These are the forces pushing back aggressively. Severe automotive price pressure across the industry, the incredibly costly compute and fleet infrastructure investments, and of course, a valuation multiple that already assumes substantial future success.
I have to mention for context on those specific headwinds, especially the intense global EV competition and integrated manufacturing pressures, you should definitely refer back to BYD EP015, EV king, or cash trap. Oh, a great reference. Yeah. BYD represents just one major competitive force in the broader global market that Tesla is navigating right now. And it really shows how brutal the pricing wars have become. A very relevant companion conversation. Moving to the third quadrant, we have the tail opportunities.
These are the massive, game-changing upside catalysts. Broader, legally authorized robotaxi deployment with proven profitable unit economics. And the successful commercial deployment of their Optimus humanoid robots in actual workplaces. And the risks? Finally, the tail risks. These are the sudden, severe mechanisms we have to monitor closely. So a material autonomy liability shock from an accident. A sudden operating restriction shock from regulators.
Or severe disruptions in global battery and mineral trade supply. So we have the drivers pushing them forward. Brutal headwinds holding them back. Massive tail opportunities and serious tail risks. These four quadrants perfectly establish the economic forces at play. But I think they lead us naturally into what the research calls the alpha gap. Yes. This is the core thesis we need to arrive at. The way I see the alpha gap, it's like having a brilliant architectural blueprint for a towering new skyscraper.
It looks amazing on paper. The 3D renders are gorgeous. And it gets everyone, the public, the city planners, the investors, incredibly excited. Right. But having the blueprint, no matter how detailed, isn't the same as having the building. You still need the years of time, the zoning permits, and the massive, grueling capital to actually pour the concrete floor by floor. That is a perfect analogy. The alpha gap is the vast space between Tesla's image as a rapidly monetizing AI platform and the grueling reality of the capital, the time, the regulatory approvals, and the operational heavy lifting required to actually create free cash flow.
Yeah. As we said earlier, a kick-flipping roadster is phenomenal at demonstrating engineering brilliance and strengthening the brand aura. But attention alone does not fund a capital expenditure program that exceeds $25 billion. That takes concrete operational cash flow from selling products at a margin. It really puts the focus on the difference between developing groundbreaking technology and actually monetizing it, which reminds me of another deep dive we did.
Another great one. Another great one. Yeah. That conversation contrasted the incredible reality of supplying the world's compute power versus the challenge their customers face in actually funding and monetizing that compute. Another great companion piece for you to explore. Absolutely. Now, when looking at all this mixed data, the incredible technological blueprints, the compressed 1.4% margins, the high 341x valuation, the multi-model AI research panel weighs the evidence quite differently.
How does a panel of AI models digest all this? What is the debate among the research? Well, the panel represents perspectives drawn from several underlying models evaluating the same data. We don't have an established numerical split or a specific count of how many models fall into which camp, but there are clearly differing emphases. Okay, like what? Well, the optimistic perspectives within the panel lean heavily into the long-term compounding value of massive fleet data, the rapid growth of the energy storage business, and the holy grail of recurring software revenue.
And the skeptics? The skeptical perspectives within the panel, however, stress the gritty reality of current manufacturing margins, the massive upfront capital costs required, the logistical nightmare of running physical fleet operations, and, of course, the sheer weight of the current valuation multiple. So the core debate isn't whether the technology is cool.
Everyone agrees it's cool. The debate is whether the recurring software subscriptions and the utility energy cash can fundamentally change the return profile of the entire massive automotive group. Exactly. And the quarterly model path gives this debate a very specific timetable. Looking ahead, Tesla's next confirmed financial results are for Q3, coming up on October 21st, after the U.S. market close. The live Q&A starts at 17:30 New York time, which is 01:30 in Dubai, on October 22nd.
And we actually already know the delivery volumes for Q3, right? They announced 486,532 deliveries, along with 13.7 gigawatt hours of storage deployment back on October 2nd. Correct. The raw delivery volume is already a known factor. The real test on October 21st won't be the car count. It will be watching the operating cash generation against the massive capex spending, alongside the underlying automotive margins and the true economics of that storage deployment.
So how does the quarterly path map out this debate going forward, month by month, year by year? The averaged base case lays out a very specific conditional path, all measured as cumulative price changes from that $368.13 starting mark. It projects a decline to roughly negative 7.8% by December 2026. Okay. Then it trends further down to negative 15.9% by September 2027. It reaches its softest point, a trough of negative 18.3% in March 2028.
After that trough, we see a conditional recovery moving back toward negative 4.9% by September 2031. It's fascinating to me that the absolute trough in the model hits in early 2028 because 2028 is exactly the production ambition management just set for that new flying roadster. It is a critical research checkpoint. The economic interpretation of this path is that the period from now up to 2028 will be characterized by intense pressure as operating margins and massive investments are severely tested.
The recovery in the later years is strictly conditional. It only happens if the software, the storage business, and the massive new platforms successfully earn their upfront costs back. I want to clarify something about the timeline of this research for you, the listener. The expert research panel's September findings were actually more skeptical than their July findings regarding Tesla's ability to convert its technological optionality into actual cash at this high valuation.
That's right. And it is important to understand that part of that shift is due to the composition of the research panel itself. The panel broadened from a single underlying model in July to several models in September. Makes sense. Yeah. That inclusion naturally changes the consensus alongside the evolving business evidence that was available at the time. But the key here is the chronology, just to be crystal clear. The Q3 operating update from October 2nd and those spectacular Roadster demos from October 16th all came after that September research was finalized.
Yes. So those October events are subsequent context for our discussion today. They are not the cause of the earlier panel shifts. That is a vital distinction. The models didn't downgrade because of a kickflip. The upcoming October 21st financial results will be the real world-world test of operating cash and margins. Yeah. This overarching challenge, you know, how you fund massive transformational change while trying to maintain current factory operations,
is something we explored deeply in our last published stock conversation, Volkswagen EP018, the price of a hard reset. It is a shared, brutal challenge across the entire industry, whether you are a legacy automaker or a tech pioneer. Okay. So this brings us to the ultimate critical thinking question. We have laid out the skeptical thesis, the contracting margins, and the sheer weight of the $25 billion of capital required. What proves the skeptics wrong? What are the invalidation tests? Well, the skeptical thesis weakens significantly if we see a sustained, undeniable automotive margin recovery,
exceptionally strong and profitable storage economics, and robust recurring cash from software and robotaxi operations. So they basically have to deliver on everything? Pretty much. If those elements can sufficiently fund the massive over $25 billion investment program and still leave durable free cash flow for the company, meaning if you see real paid utilization, transparent fleet costs, operating cash fully covering the capex,
and less dependence on non-operating paper gains, then the skeptics are proven absolutely wrong. And on the flip side, what confirms the skeptics' fears? The skeptical thesis strengthens if revenue growth repeatedly fails to translate into operating margins, if capital expenditures persistently outstrip operating cash flow, or if these incredible products repeatedly miss their stated economic milestones. And a spectacular prototype, no matter how many kickflips it does or how fast it launches,
doesn't settle those balance sheet tests by itself. No, it doesn't. A prototype captures global attention, but it does not print operating cash. So what does this all mean for you? The Roadster undeniably proves that Tesla can command global attention and attempt truly extraordinary physics-defying engineering. But as a listener and as an investor, your job is to watch the spreadsheet, not just the spectacle. Right. You have to monitor if the actual earnings and the free cash generation can keep pace with that incredibly demanding 341x price multiple.
It is the ultimate test of turning brilliant architectural blueprints into a profitable cash-flowing skyscraper. Exactly. I highly encourage you to explore the full depth of Tesla's analysis and the complete 20-quarter return paths over at iPulse AI. And of course, keep listening, watching, or subscribe to AI Investment Edge to stay informed. We mentioned three incredibly relevant companion conversations today. BMW, BYD, and NVIDIA.
They provide fantastic context for the competitive forces and capital costs we discussed here today. Stay tuned for SpaceX next on AI Investment Edge. How do launch and global connectivity turn extraordinary engineering into cash? That is our next question.